

Nasdaq faces a higher hurdle as inflation and yields test the AI trade
Hot CPI pushes yields higher, weighing on stocks as investors await key earnings from big Tech.
The Nasdaq 100 is coming under renewed pressure following Wednesday’s hotter-than-expected US CPI report, with the index slipping below 30,000 as investors reassess the combination of elevated valuations, persistent inflation and higher Treasury yields. The issue is no longer simply whether Big Tech can continue growing, it is whether earnings can grow quickly enough to justify those valuations when the alternative risk-free return has become considerably more attractive.
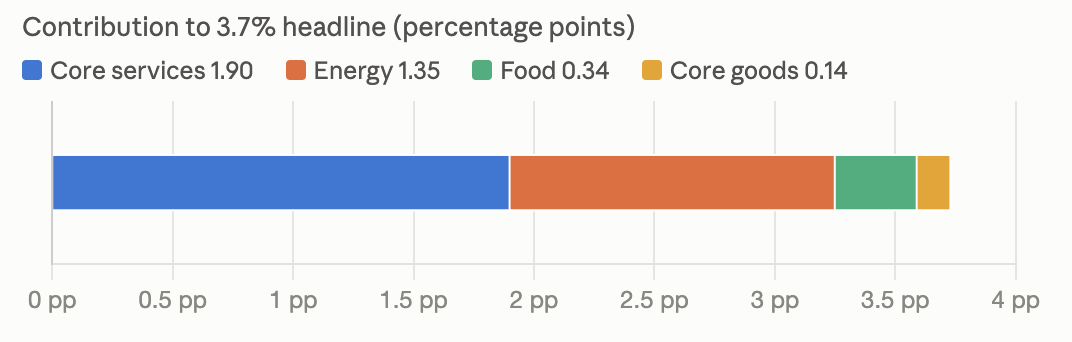
The CPI report reinforced that US inflation remains too persistent for the Federal Reserve to comfortably turn dovish. More importantly, the strength in core services suggests price pressures cannot be explained solely by the energy shock. That has strengthened expectations for another Fed hike and kept long-term Treasury yields above 5%, raising the discount rate applied to future corporate earnings.
Source: bls.gov
The hurdle rate is rising
This creates an increasingly demanding environment for growth stocks. When government bonds offered very little return, investors had greater incentive to accept high equity valuations in exchange for future growth. With Treasuries now yielding above 5%, that calculation has changed.
The Nasdaq therefore needs something more than good earnings. Big Tech increasingly needs exceptional earnings, strong guidance and evidence that enormous AI investment programmes are producing sufficient returns to compensate investors for taking equity risk. That makes the current earnings season particularly important. Hyperscalers have spent heavily on data centres, semiconductors and power infrastructure, and investors have so far rewarded that investment on the assumption that AI will produce substantial future cash flows. As borrowing costs rise, patience for those returns may become shorter.
Narrow breadth increases the stakes
The other vulnerability is market breadth. The headline indices remain relatively close to record highs, but leadership has become increasingly concentrated in technology and communication-services companies. That concentration has helped shield the broader market from the rise in yields because the largest technology companies generally have strong balance sheets, substantial cash generation and powerful earnings momentum.
But it also creates a potential weakness. If the handful of companies carrying the index disappoint, there are increasingly few areas of the market positioned to compensate. That makes upcoming Big Tech earnings about more than individual companies. They will effectively test the fundamental justification for the broader equity rally.
Nasdaq technical outlook
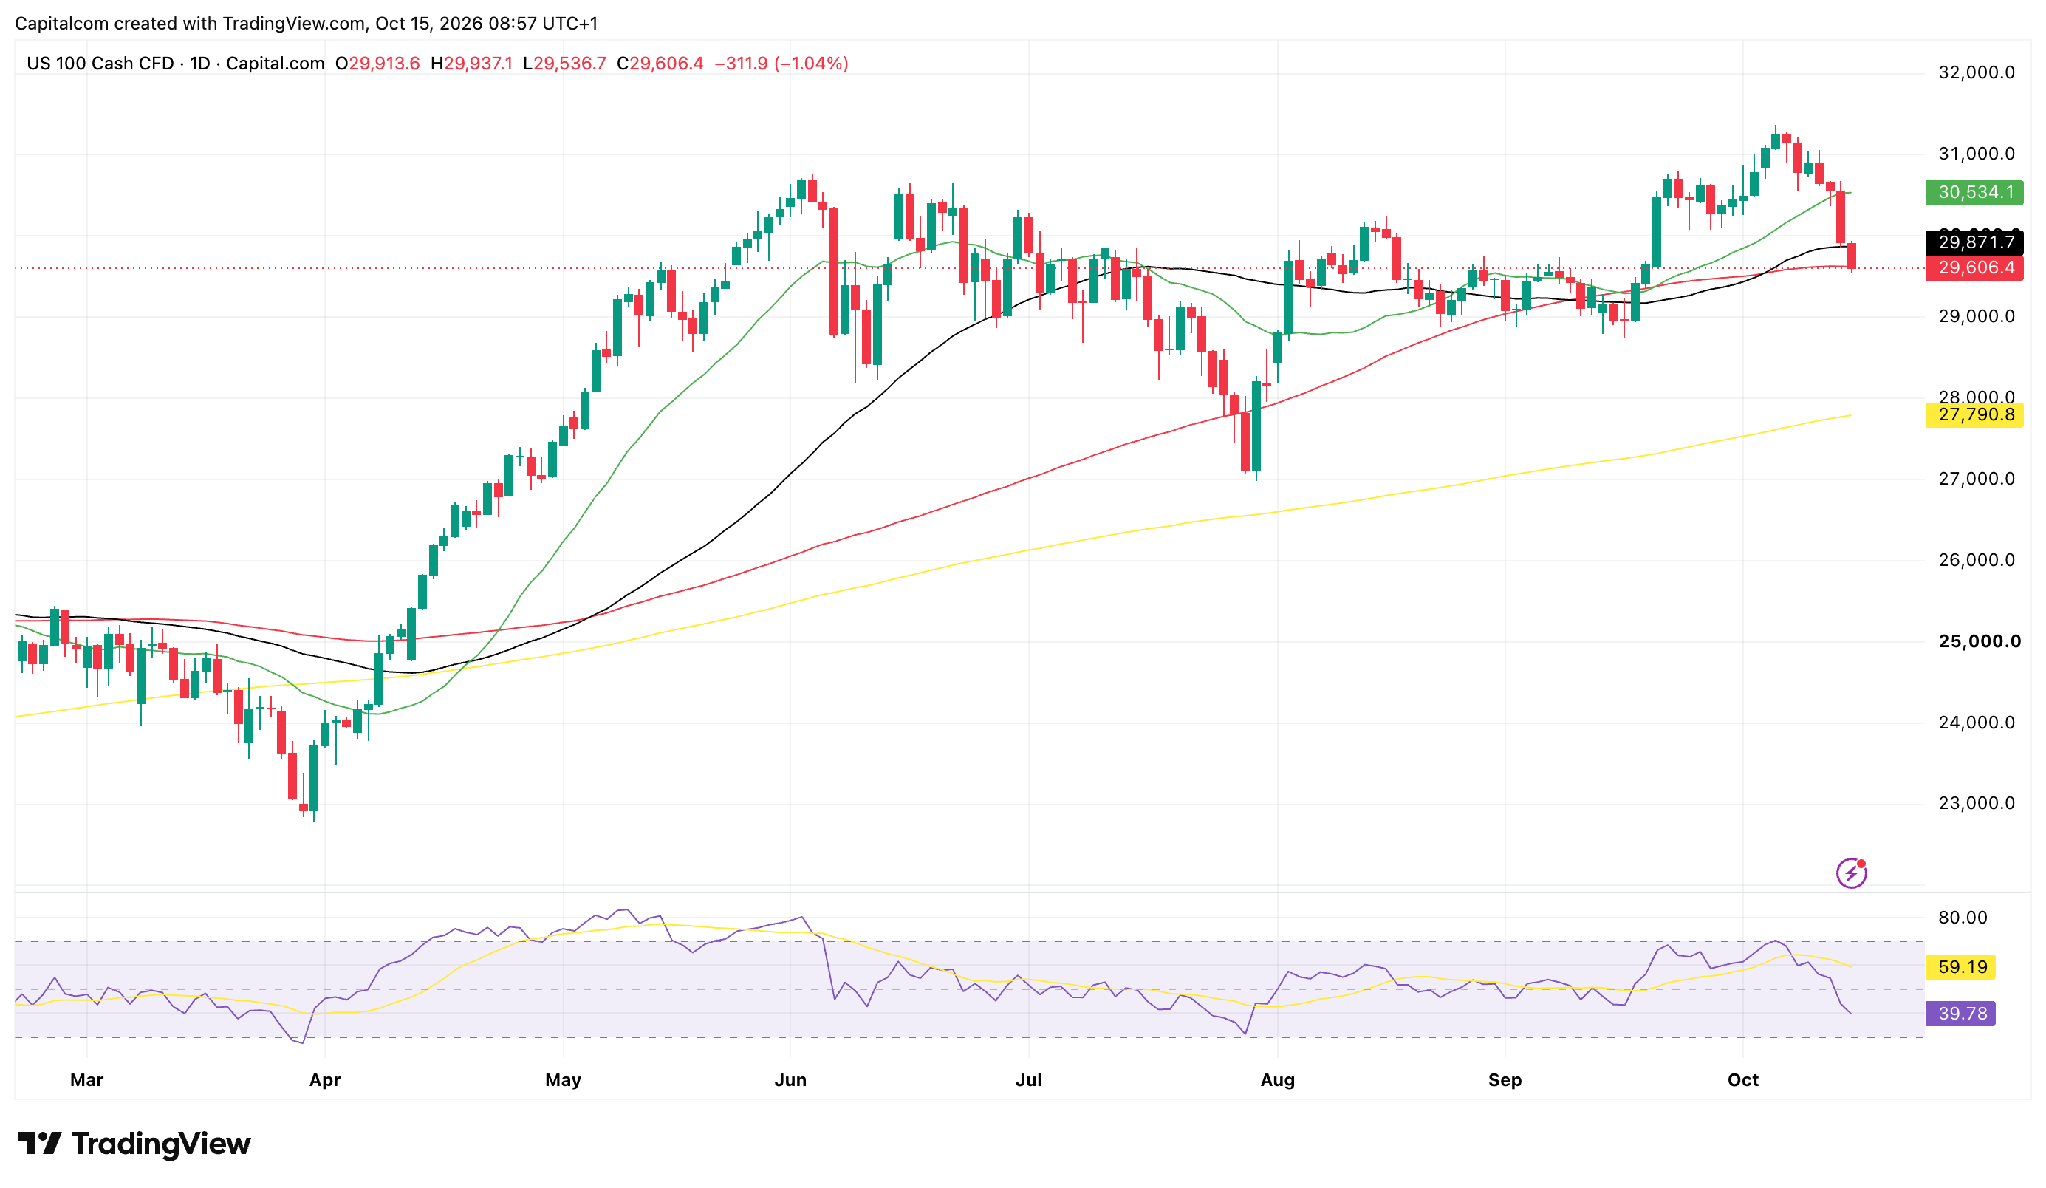
The chart is beginning to reflect that deterioration in sentiment. The Nasdaq 100 has fallen sharply from its October high above 31,000, breaking below its short-term moving average and now testing the 29,500–29,900 region around its 50- and 100-day averages. RSI has fallen towards 40, confirming the loss of momentum without yet signalling deeply oversold conditions.
US tech 100 daily chart
Past performance is not a reliable indicator of future results.
A sustained break below 29,500 could expose 29,000, while the 200-day average around 27,800 represents a more significant downside level. Conversely, reclaiming 30,500 would stabilise the short-term picture, with the 31,000–31,300 region remaining the key hurdle for another attempt at record highs.
Big Tech now needs to deliver
The medium-term outlook does not necessarily need to turn bearish. Earnings expectations remain strong, economic activity has proven resilient and AI investment continues to offer a powerful structural growth story. But the conditions required to sustain the rally have become more demanding.
The biggest risk may now be the combination of narrow market leadership and a rising risk-free rate. If Big Tech demonstrates that AI spending is translating into accelerating revenue, margins and cash flow, strong earnings could continue to offset the pressure from higher yields. If those returns disappoint while Treasury yields remain above 5%, however, the concentration that has protected the Nasdaq from the bond sell-off could quickly become its biggest vulnerability.