

Take-Two heads into GTA VI launch with a weaker quarter and full-year outlook unchanged
Take-Two’s Q2 Net Bookings came in below guidance, but GTA VI pre-orders are at ‘unprecedented levels’. What the launch could mean for TTWO stock.
After the close on 9 November, Take-Two reported Net Bookings of USD 1.60bn for its fiscal second quarter of 2027 (July–September), down 18% year on year and slightly below its own guidance of USD 1.62–1.67bn. The company said NBA 2K27 came in below internal forecasts, according to its results presentation. The GAAP net loss narrowed to USD 54.0m.
Grand Theft Auto VI reaches consoles today, 19 November. In its results, Take-Two reiterated its outlook for fiscal 2027 Net Bookings of USD 8.0–8.2bn, up from USD 6.72bn in fiscal 2026, and said pre-orders continue to reach "unprecedented levels".
Key data
| Ticker / exchangeTTWO · Nasdaq | SectorCommunication Services (video games) | Market capUSD 40.6bn |
|---|---|---|
| Previous close (17/11)USD 203.93 | Close (18/11)USD 216.61 (+6.2%) | 52-week rangeUSD 183.86 – 265.94 |
| DividendNone | Beta (5Y)0.92 | Next resultsFeb 2027 (TBC) |
Source: Yahoo Finance (TTWO quote and key data, close on 18/11/2026); StockAnalysis.com (market cap, based on 187.21m shares outstanding).
Past performance is not a reliable indicator of future results.
Overview
Take-Two publishes games through three labels: Rockstar Games (Grand Theft Auto, Red Dead Redemption), 2K (NBA 2K, Borderlands, WWE 2K, Civilization, BioShock) and Zynga (mobile games such as Toon Blast, Match Factory!, Empires & Puzzles, Words With Friends and Zynga Poker). Its fiscal year ends on 31 March, so fiscal Q2 2027 covers July to September 2026. Net Bookings, the company's main operating metric, measures what was sold in the period, before revenue deferrals. In the quarter, recurrent consumer spending (in-game purchases, virtual currency, add-on content and in-game advertising) made up 81% of Net Bookings. By platform, mobile accounted for 45%, console 46% and PC 9%, and 98% of sales were digital. The United States generated 60% of Net Bookings. Grand Theft Auto VI is expected to become available on PlayStation 5 and Xbox Series X|S today, 19 November; no PC version has been announced.
Profitability
In fiscal 2026 (to March 2026), Net Bookings rose 19% to USD 6.72bn and GAAP revenue rose 18% to USD 6.66bn, but Take-Two still reported a GAAP net loss of USD 298m. In fiscal Q2 2027, Net Bookings fell 18% against a strong prior-year quarter, which included the launch of Borderlands 4, and GAAP revenue fell 16% to USD 1.50bn. Mobile Net Bookings fell 13.5% to USD 708m. Gross margin improved to 57.5% from 55.3%, and operating expenses fell 9% to USD 978m, led by lower selling and marketing costs. Even so, the operating loss widened to USD 117.5m (−7.8% margin). The net loss narrowed to USD 54.0m, helped by a USD 57.9m tax benefit. Free cash flow was −USD 143m, as capital expenditure rose to USD 138m in the quarter. The company's non-GAAP EBITDA was USD 92.2m, down from USD 116.7m.
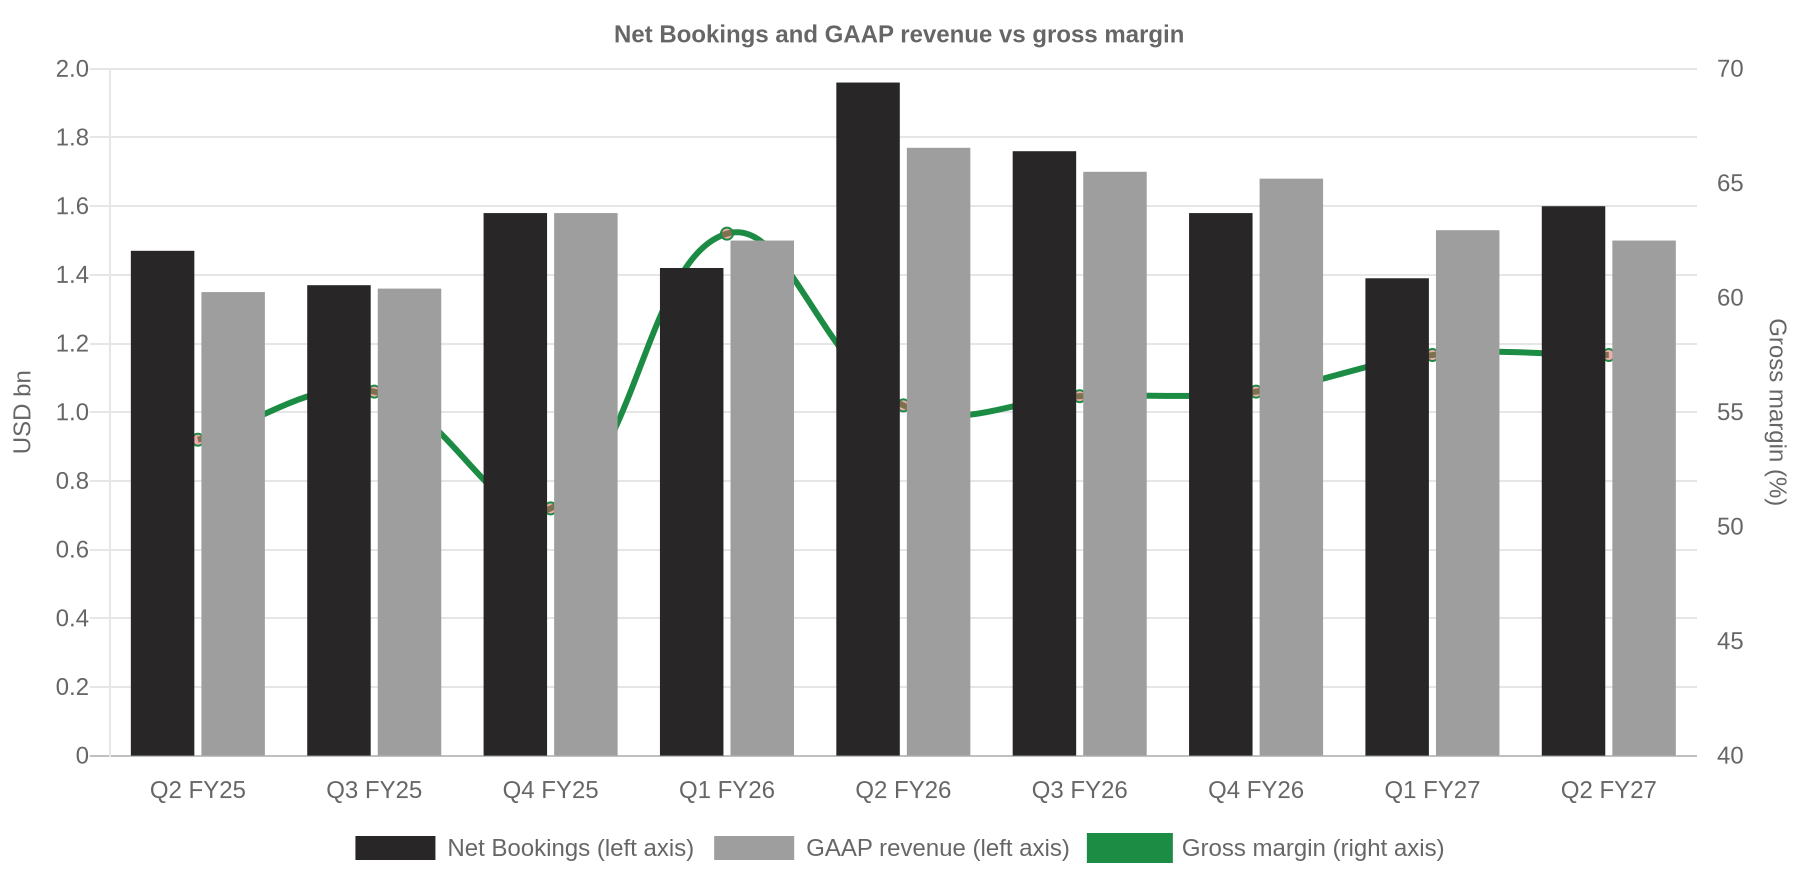
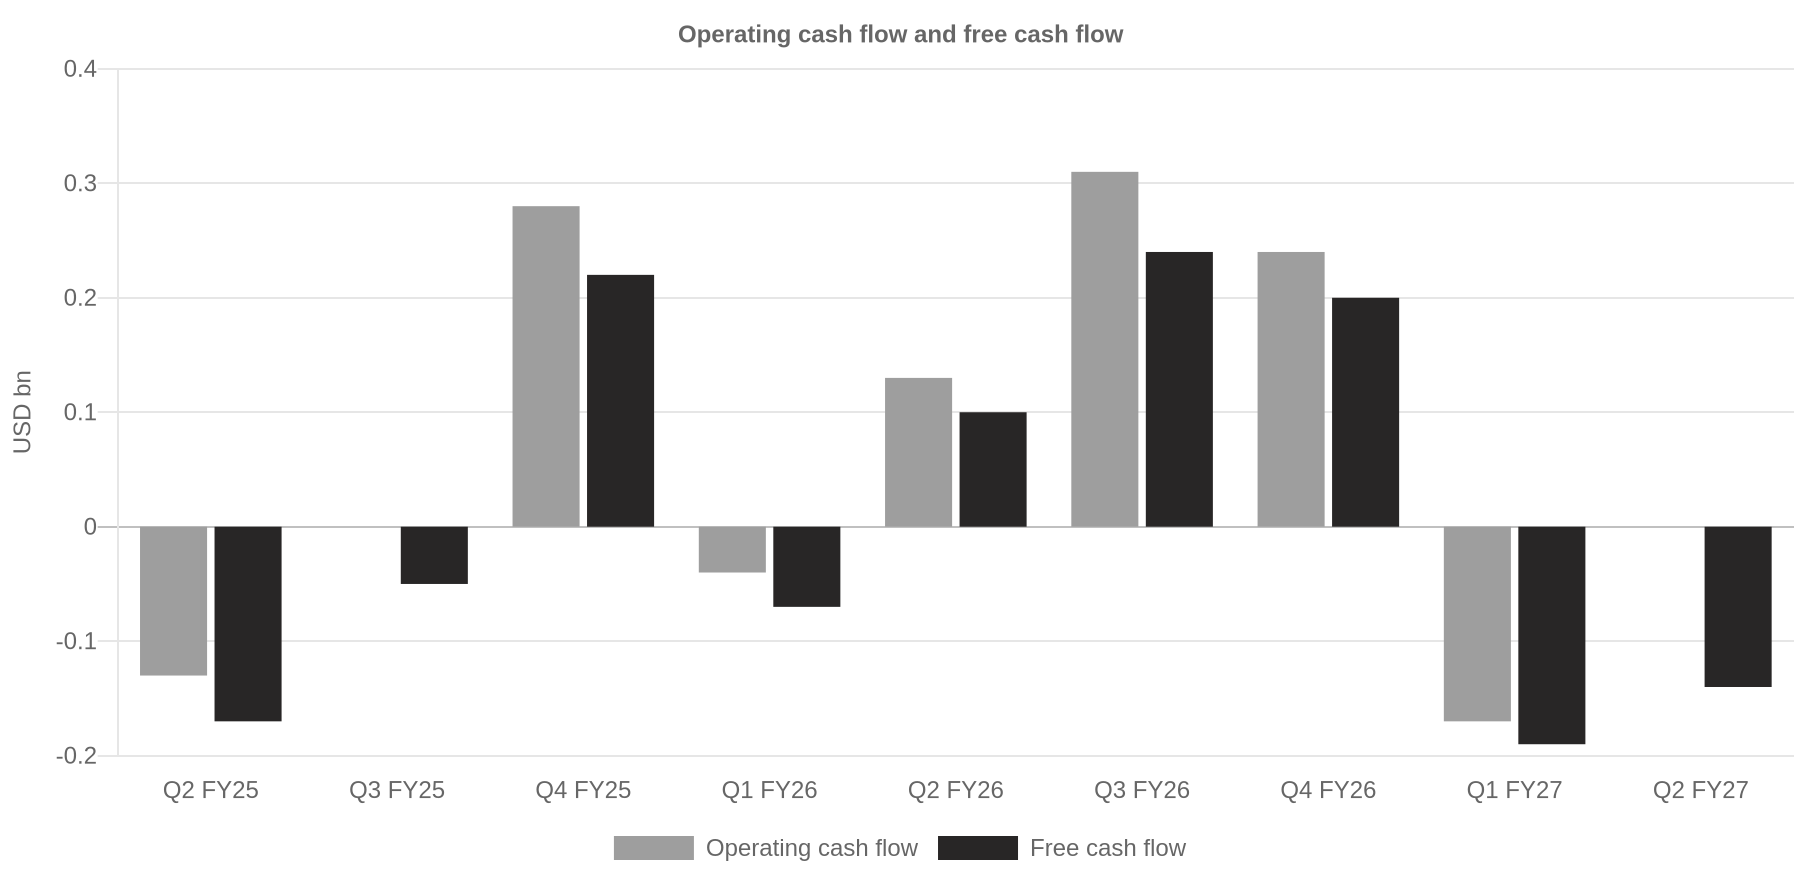
Source: Take-Two filings (8-K), Capital.com calculations. USD bn. Period covered: Q2 FY25 (July–September 2024) to Q2 FY27 (July–September 2026); data as of the Q2 FY2027 results release on 09/11/2026. Fiscal quarters: the fiscal year ends on 31 March, so Q2 FY27 covers July–September 2026. FCF = operating cash flow − purchases of fixed assets. Quarterly cash flows are derived from year-to-date figures.
Past performance is not a reliable indicator of future results.
Quarterly trend: Q/Q and Y/Y changes
| USD m | Q2 FY25 | Q3 FY25 | Q4 FY25 | Q1 FY26 | Q2 FY26 | Q3 FY26 | Q4 FY26 | Q1 FY27 | Q2 FY27 |
|---|---|---|---|---|---|---|---|---|---|
| Net Bookings | 1,475 | 1,373 | 1,582 | 1,423 | 1,960 | 1,757 | 1,580 | 1,386 | 1,601 |
| % Q/Q | +21.1% | −6.9% | +15.2% | −10.0% | +37.8% | −10.4% | −10.1% | −12.3% | +15.5% |
| % Y/Y | +2.1% | +2.7% | +17.3% | +16.8% | +32.9% | +27.9% | −0.1% | −2.6% | −18.3% |
| GAAP revenue | 1,353 | 1,360 | 1,582 | 1,504 | 1,774 | 1,699 | 1,680 | 1,534 | 1,497 |
| % Q/Q | +1.1% | +0.5% | +16.4% | −5.0% | +18.0% | −4.2% | −1.1% | −8.7% | −2.4% |
| % Y/Y | +4.1% | −0.5% | +13.1% | +12.4% | +31.1% | +24.9% | +6.1% | +2.0% | −15.6% |
| Gross profit | 728 | 760 | 803 | 945 | 980 | 946 | 939 | 882 | 860 |
| Operating income | −297 | −132 | −3,777 | 22 | −98 | −39 | 11 | −36 | −118 |
| EBT | −324 | −153 | −3,802 | −14 | −116 | −56 | −13 | −49 | −112 |
| Net income | −366 | −125 | −3,726 | −12 | −134 | −93 | −60 | −34 | −54 |
| Operating cash flow | −128 | −5 | 279 | −45 | 128 | 305 | 235 | −169 | −5 |
| Capex | −37 | −43 | −54 | −25 | −32 | −69 | −37 | −25 | −138 |
| Free cash flow | −165 | −48 | 225 | −70 | 96 | 236 | 199 | −194 | −143 |
| Gross margin | 53.8% | 55.9% | 50.8% | 62.8% | 55.3% | 55.7% | 55.9% | 57.5% | 57.5% |
| Operating margin | −22.0% | −9.7% | −238.7% | +1.4% | −5.5% | −2.3% | +0.6% | −2.3% | −7.8% |
Source: Take-Two filings (8-K, 10-Q, 10-K), Capital.com calculations. USD m. FY = fiscal year. Take-Two's fiscal year ends on 31 March, so FY27 (fiscal 2027) runs from April 2026 to March 2027 and Q2 FY27 covers July–September 2026. Q/Q = change versus the previous quarter; Y/Y = change versus the same quarter a year earlier. n.m. = not meaningful (negative value). Net Bookings is the company's operating metric (sales in the period before revenue deferrals). Q4 FY25 includes a goodwill impairment of about USD 3.55bn. Operating cash flow and capex for each quarter are derived from year-to-date figures.
Past performance is not a reliable indicator of future results.
Results vs guidance and consensus
GAAP revenue and the net loss came in better than the company's own guidance, but Net Bookings and recurrent consumer spending fell short, according to the company's results presentation.
| Net BookingsUSD 1.60bnBelow guidance of USD 1.62–1.67bn | GAAP net revenueUSD 1.50bnAbove guidance of USD 1.42–1.47bn | GAAP EPS−USD 0.29Better than guidance of −USD 0.84 to −0.75 |
|---|---|---|
| Recurrent consumer spending−9% Y/YGuidance of −5% | Q3 Net Bookings guidanceUSD 3.35–3.50bnConsensus USD 3.51bn | FY27 Net Bookings guidanceUSD 8.0–8.2bnReiterated |
Source: Take-Two Q2 FY2027 earnings release; Take-Two Q2 FY2027 results presentation (results and guidance); Investing.com (prior guidance and Q3 consensus estimate).
Past performance is not a reliable indicator of future results.
Solvency
At the end of September, Take-Two had net debt of USD 846m (total debt of USD 2.52bn less USD 1.67bn of cash and short-term investments), up from USD 529m in March, as operating cash flow was negative in the first half of the fiscal year. Equity stood at USD 3.67bn.
| Quarter end | Total debt | Cash + ST investments | Net debt | Equity | Net debt/TTM EBITDA | Current ratio |
|---|---|---|---|---|---|---|
| Sep 2026 | 2,520 | 1,674 | 846 | 3,674 | 1.25x | 1.09 |
| Jun 2026 | 2,520 | 1,827 | 693 | 3,608 | 0.99x | 1.06 |
| Mar 2026 | 2,518 | 1,989 | 529 | 3,511 | 0.70x | 1.24 |
| Dec 2025 | 3,069 | 2,359 | 710 | 3,496 | 1.05x | 1.14 |
| Sep 2025 | 3,067 | 2,116 | 951 | 3,432 | 1.61x | 1.15 |
| Jun 2025 | 3,065 | 2,035 | 1,030 | 3,481 | 2.58x | 1.16 |
| Mar 2025 | 3,661 | 1,466 | 2,196 | 2,138 | 11.0x | 0.78 |
| Dec 2024 | 3,658 | 1,210 | 2,448 | 5,702 | n.m. | 0.83 |
Source: Take-Two balance sheets (10-Q, 10-K and 8-K releases), Capital.com calculations. USD m. Total debt = short-term plus long-term debt, net. EBITDA = the company's non-GAAP EBITDA over the last 12 months.
Past performance is not a reliable indicator of future results.
| Fiscal year end | Total debt | Cash + ST investments | Net debt | Equity | Net debt/EBITDA | Current ratio |
|---|---|---|---|---|---|---|
| FY2026 (Mar 2026) | 2,518 | 1,989 | 529 | 3,511 | 0.70x | 1.24 |
| FY2025 (Mar 2025) | 3,661 | 1,466 | 2,196 | 2,138 | 11.0x | 0.78 |
| FY2024 (Mar 2024) | 3,083 | 776 | 2,307 | 5,668 | 8.5x | 0.94 |
| FY2023 (Mar 2023) | 3,080 | 1,014 | 2,065 | 9,043 | n.a. | 0.65 |
Source: Take-Two balance sheets (10-K and 8-K releases), Capital.com calculations. USD m. Cash + ST investments = cash and cash equivalents plus short-term investments (excluding restricted cash). EBITDA = the company's non-GAAP EBITDA for the fiscal year. n.a. = not available.
Past performance is not a reliable indicator of future results.
What happened. In the first half of fiscal 2026 Take-Two raised USD 1.22bn through a share issuance and repaid USD 600m of notes. Total debt fell from USD 3.66bn in March 2025 to USD 2.52bn in March 2026. Equity had dropped to USD 2.14bn in March 2025, after a goodwill impairment of about USD 3.55bn in the fourth quarter of fiscal 2025.
Read the figures with care. GAAP results are weighed down by the amortisation of acquired intangibles, mostly from the 2022 Zynga acquisition: USD 305.6m in the first half of fiscal 2027 and USD 623m expected for the full year. In the first half, operating cash flow was −USD 173.5m, as the company invested USD 372.4m in software development costs and licences ahead of the GTA VI launch. Management expects operating cash flow above USD 1bn in fiscal 2027, according to the company's results presentation.
Maturities and rating. USD 629m of debt is due within 12 months and USD 1.89bn later. Take-Two is rated Baa2 by Moody's (via ResearchPool) and BBB by S&P, according to Octus.
Shareholder returns
Take-Two does not pay a dividend and did not buy back shares in the period shown; treasury stock was unchanged at 23.7m shares. Shares outstanding rose from 170.8m in March 2024 to 185.4m in March 2026 and 187.2m in September 2026, a 9.6% increase, reflecting the 2025 share issuance and stock-based compensation. Stock-based compensation was USD 176.0m in the first half of fiscal 2027, up from USD 136.6m a year earlier, and the company expects USD 462m for the full year.
Relative valuation and competition
Take-Two has reported a GAAP net loss over the last 12 months, so its trailing P/E is not meaningful. On sales, it trades at about 6.3x revenue, above Roblox, Nintendo and Sony. Electronic Arts, its closest listed peer, was taken private on 4 August 2026, according to Game Informer.
| Company | Market cap (USD bn) | P/S (TTM) | EV/Sales (TTM) | EV/EBITDA (TTM) | 52-week change |
|---|---|---|---|---|---|
| Take-Two (TTWO) | 40.6 | 6.3x | 6.5x | 57.6x | −9.4% |
| Roblox (RBLX) | 33.9 | 5.7x | 5.5x | n.m. | −53.5% |
| Nintendo (NTDOY, ADR) | 66.1 | 4.8x | 4.0x | 15.6x | −33.5% |
| Sony Group (SONY) | 159.0 | 1.9x | 2.0x | 11.1x | −7.0% |
Source: StockAnalysis.com (statistics as of 12/11/2026, updated to closing prices on 18/11/2026; Capital.com calculations). n.m. = not meaningful (negative EBITDA). TTM = last 12 months.
Past performance is not a reliable indicator of future results.
Other Take-Two multiples: EV/EBITDA is about 57.6x, as shown in the table above. Consensus expects EPS of USD 1.72 in fiscal 2027 (to March 2027) and USD 5.65 in fiscal 2028, according to Yahoo Finance (10/11/2026), which implies P/E multiples of about 126x and 38x at the 18 November close (Capital.com calculations). The company's own guidance for fiscal 2027 GAAP EPS is USD 0.57–0.75. Consensus expects revenue of USD 8.56bn in fiscal 2027 and USD 9.21bn in fiscal 2028 (+7.5%), according to Yahoo Finance.
Competition.
- Console and PC: Take-Two competes with Sony (PlayStation Studios), Microsoft (Xbox and Activision Blizzard), Nintendo and Ubisoft, as well as Electronic Arts, now privately owned.
- Sports: NBA 2K competes for players' time and spending with EA Sports titles. The company said NBA 2K27 came in below its internal forecasts for the quarter.
- Mobile: Zynga competes with other free-to-play publishers and platforms such as Roblox; Take-Two's mobile Net Bookings fell 13.5% year on year in the quarter.
- Platforms: sales depend on the PlayStation and Xbox stores and on the Apple and Google app stores, which take a share of revenue.
Analyst consensus. The average price target is USD 283.96, in a range of USD 170 to USD 330, from 29 analysts, according to data compiled by Yahoo Finance (10/11/2026). On 7/11, Macquarie started coverage with a USD 300 target, according to Yahoo Finance. These targets reflect the views of third-party analysts, not Capital.com.
Catalysts and risks
The next test is the launch of Grand Theft Auto VI today, 19 November, which falls in the fiscal third quarter (October–December).
Catalysts
- The GTA VI launch on 19 November and its first weeks of sales. Management guides fiscal Q3 Net Bookings of USD 3.35–3.50bn.
- Critics' scores: Metacritic of 99, from 146 reviews (BigGo Finance, 18/11/2026). Third-party figure, not the company's.
- Pre-orders: 15.9m copies and USD 1.54bn, according to Sensor Tower estimates (TradersUnion, 18/11/2026). Third-party estimate, not the company's.
- Recurrent consumer spending guided up about 12% year on year in Q3, driven by GTA and NBA 2K, according to the company's results presentation.
- Management's expectation of operating cash flow above USD 1bn in fiscal 2027, according to the company's results presentation.
- The pipeline: PGA TOUR 2K27, WWE 2K27, Judas, the next BioShock, Project ETHOS and the mobile titles CSR 3 and Top Goal (dates to be announced).
- Any announcement of a PC version of GTA VI, which has not been announced so far.
Risks
- Concentration: the fiscal 2027 outlook depends heavily on one title. GTA VI was delayed twice before the current 19 November date.
- NBA 2K27 below internal forecasts and recurrent consumer spending down 9% in Q2.
- Mobile: Net Bookings down 13.5% year on year in Q2, with player acquisition costs among the factors the company lists.
- Q3 Net Bookings guidance below the consensus estimate of USD 3.51bn, according to Investing.com.
- GAAP net losses in all nine quarters shown, large amortisation of acquired intangibles and a history of impairments (about USD 3.55bn in Q4 FY25).
- Dilution and stock-based compensation (USD 462m expected in fiscal 2027), and net debt of USD 846m.
- Launch: Oppenheimer points to cyberattacks on consoles on launch day as the main risk, and is watching whether GTA VI pulls engagement away from Roblox (Investing.com, 18/11/2026; third-party opinion).
- Dependence on the installed base of PlayStation 5 and Xbox Series X|S and on game pricing.
Technical analysis
Take-Two's shares have been trading sideways since February 2025, with the highs marked by the resistance area between around USD 254 and USD 265 and the lows by the support area between around USD 185 and USD 192, both shown on the chart.
On 10 November, the first trading day after the results, the shares rose 8.3% to USD 224.64. Over the last three sessions, volatility in the shares rose sharply, with intraday ranges above 5% every day (10.4% on 16 November, 8.7% on 17 November and 6.0% on 18 November). However, the shares remain within the range between the main support and resistance areas.
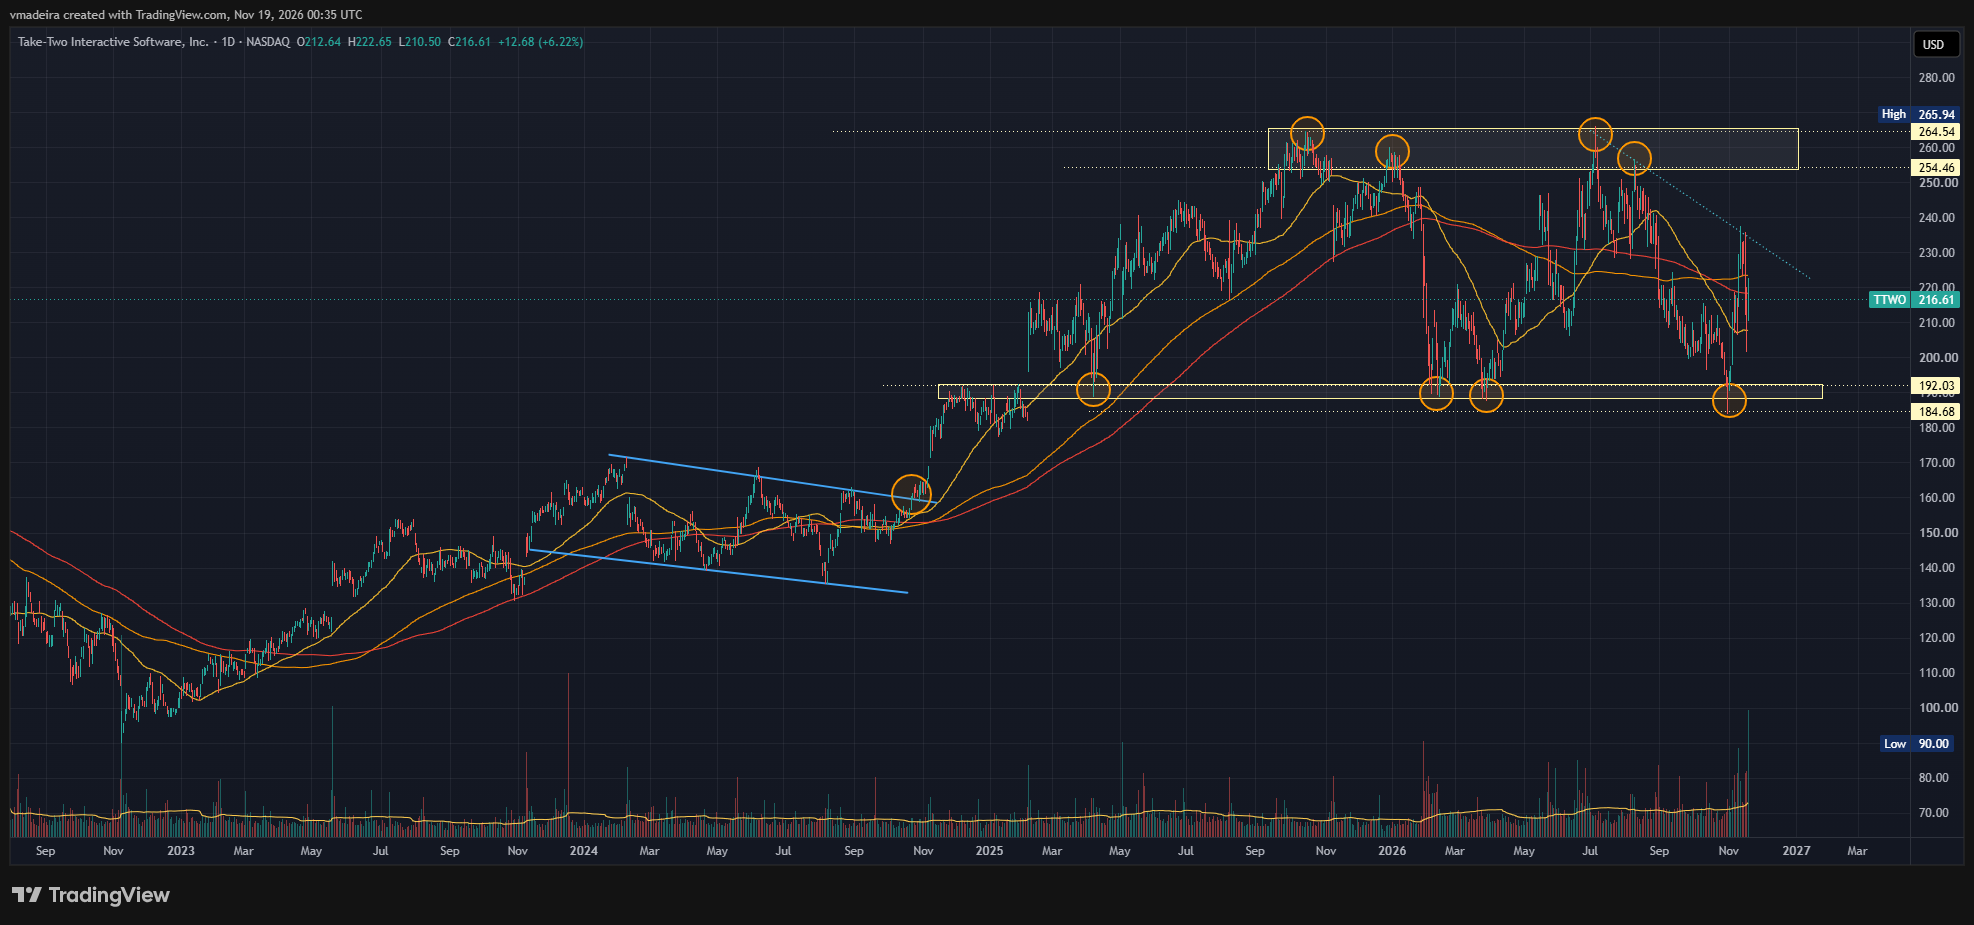
Source: TradingView (Capital.com), TTWO daily chart, November 2023 to 18 November 2026; data as of the close on 18/11/2026 (21:00 UTC).
Past performance is not a reliable indicator of future results.
Reference data: 52-week range USD 183.86–265.94 (high on 07/07/2026, low on 30/10/2026); close on 18/11 USD 216.61 (+6.2%); 50-day and 200-day simple moving averages about USD 208 and USD 218 (Capital.com calculations from daily closes, StockAnalysis.com); change in 2026 to 18/11: −15.4%; 52-week change: −9.4%.
Summary
Take-Two reaches the GTA VI launch with a weaker second quarter but an unchanged full-year outlook that depends largely on one title.
Strengths
- Fiscal 2027 Net Bookings guidance of USD 8.0–8.2bn reiterated (fiscal 2026: USD 6.72bn), with GTA VI pre-orders at "unprecedented levels", according to the company.
- 81% of Net Bookings from recurrent consumer spending and 98% of sales digital.
- Q2 GAAP revenue and net loss better than the company's guidance, with operating expenses down 9%.
Factors to watch
- Q2 Net Bookings down 18% and below guidance; NBA 2K27 below forecast; mobile down 13.5%.
- Q3 Net Bookings guidance below the consensus estimate, according to Investing.com.
- Net debt of USD 846m, negative free cash flow in the first half, and a rising share count.
- GAAP net losses in every quarter shown.