

Markets end a pivotal central-bank week on firmer footing
A busy week of central bank meetings leaves markets on firmer footing despite several rate hikes and hawkish messaging.
A pivotal week is coming to an end with risk appetite recovering, despite one of the most synchronised bouts of global monetary tightening in some time. The Fed delivered the expected 25bp hike to 3.75–4.00% and signalled that further tightening remains possible, following the ECB had rate rise the previous week. The Bank of England resisted joining them, holding at 3.75% by 6–3, although the three dissenters wanted a hike and the Bank warned that persistent Middle East-driven energy inflation could eventually require tighter policy. The BoJ rounded out the week by raising rates from 1% to 1.25%, a 31-year high, although two dissents and the absence of a more aggressive signal gave the decision a relatively dovish interpretation.
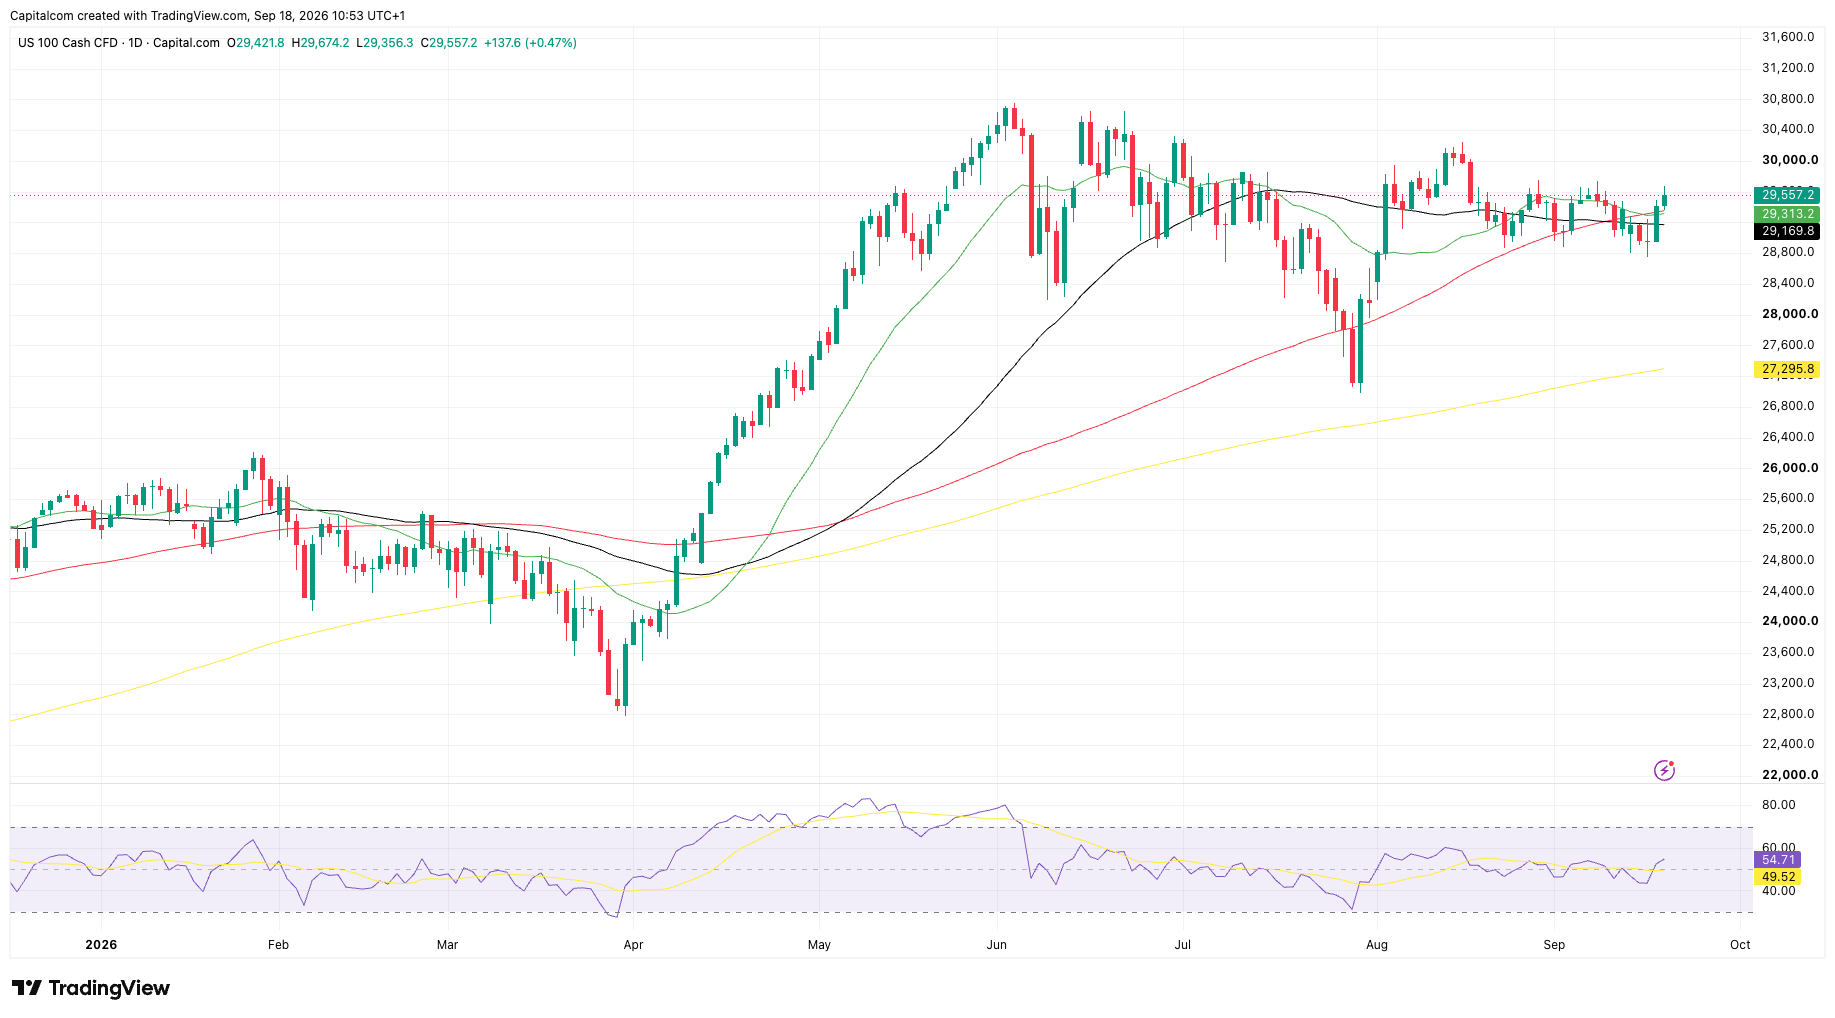
Throughout the turmoil, equities have remained resilient. After initially struggling with the Fed's hawkish message, risk appetite improved into the latter part of the week, helped by some relief in oil and the absence of a fresh surge in long-term yields. The resilience suggests investors are distinguishing between higher rates driven by persistent inflation and a fundamentally deteriorating growth outlook; for now, the latter has not become the dominant concern.
US Tech 100 daily chart
Past performance is not a reliable indicator of future results.
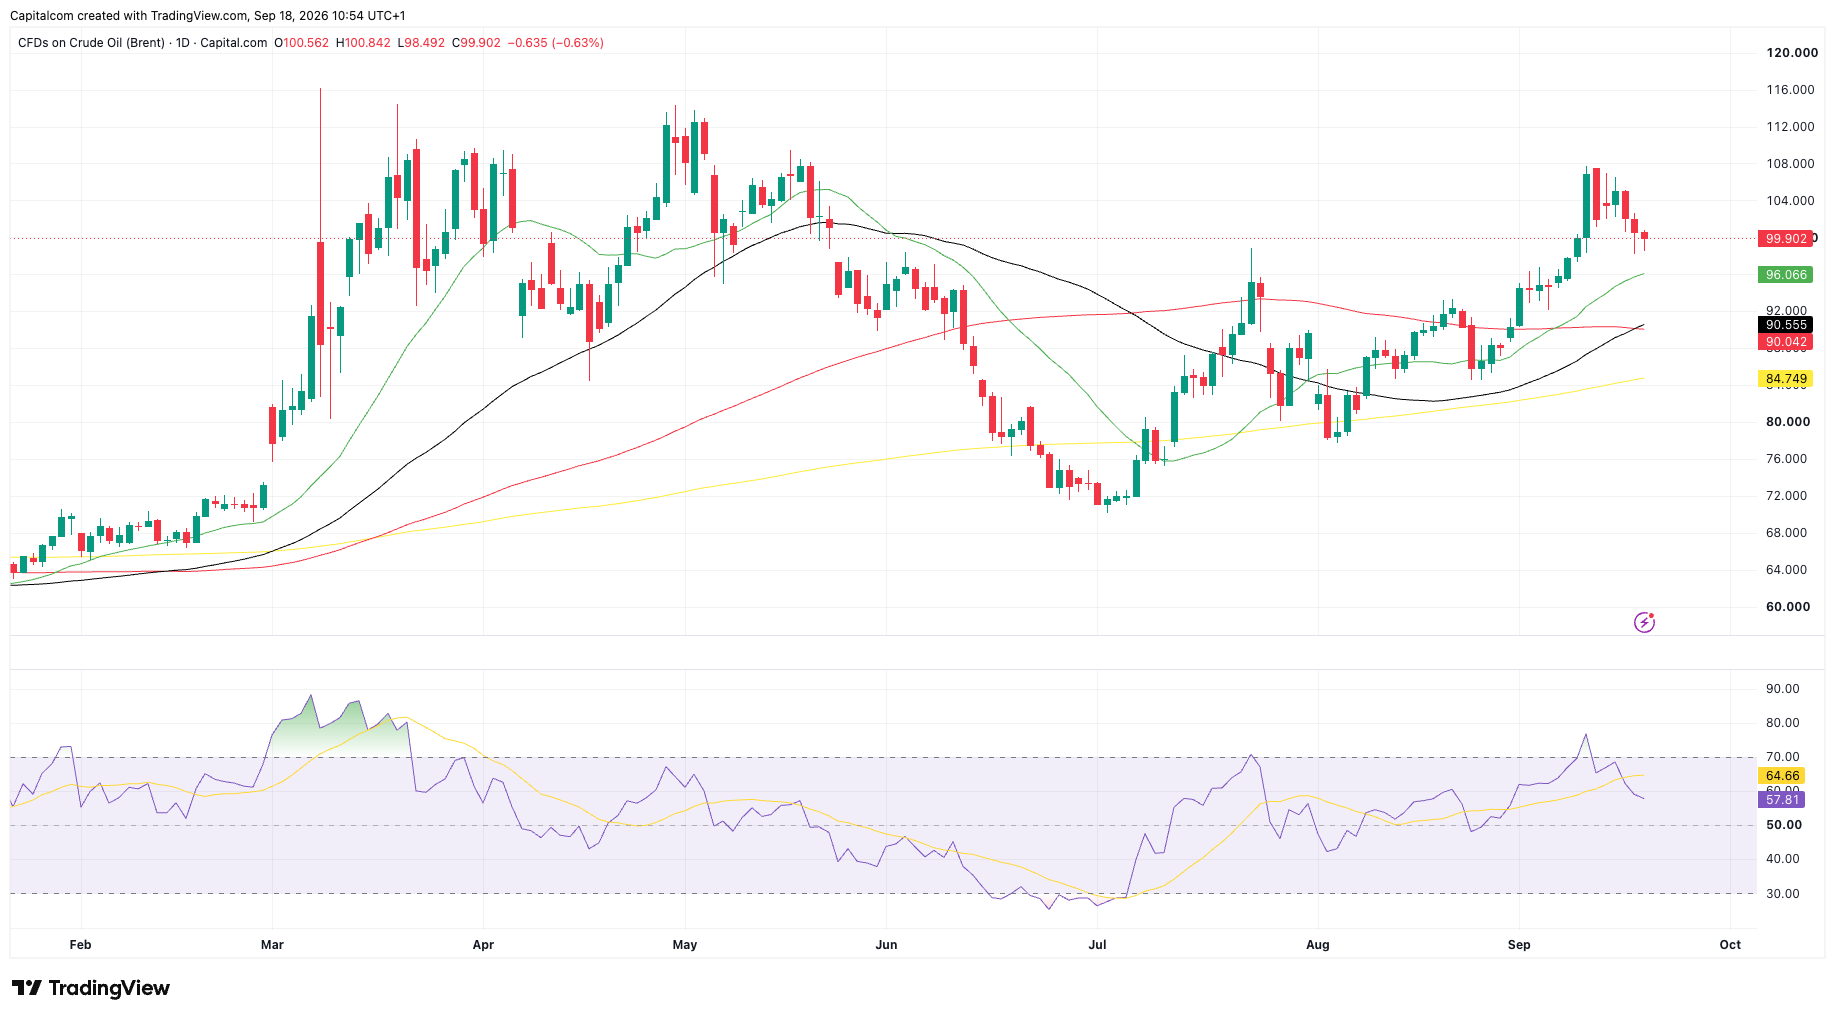
Oil is nevertheless ending the week lower, after another volatile period dominated by developments in the Middle East. The retreat has offered some relief after Brent's earlier surge above $100 intensified fears that the energy shock would force central banks into a much more aggressive tightening cycle. But the geopolitical premium remains significant, and Hormuz and Saudi infrastructure remain important tail risks. Gold, meanwhile, is ending the week higher, supported by geopolitical uncertainty and longer-term fiscal concerns even as elevated real yields continue to provide a counterweight.
Brent crude daily chart
Past performance is not a reliable indicator of future results.
The bond market arguably remains the most important cross-asset signal. Treasury yields are hovering close to their recent highs, with the 10-year around the psychologically important 5% region. The Fed may have reinforced its inflation-fighting credentials, but heavy government borrowing, elevated term premium and growing private-sector competition for capital mean long yields remain supported by forces that monetary policy alone cannot easily resolve. That leaves equities in a delicate position: the current rally can coexist with high yields while earnings and growth remain resilient, but another decisive leg higher in borrowing costs would put valuations—particularly in technology—back under pressure.
What to watch next week
Next week should be quieter from a central-bank perspective, which gives markets an opportunity to digest this week's decisions. The US calendar includes flash manufacturing and services PMIs on Wednesday, followed by jobless claims, housing data, durable goods and the final University of Michigan consumer survey later in the week. Several Fed officials are also scheduled to speak, so investors will be looking for evidence of how broadly Warsh's appetite for further tightening is shared across the FOMC.
The bigger swing factor may once again be oil. A continued retreat would remove some pressure from inflation expectations and yields, potentially allowing the improvement in risk appetite to continue. Another escalation in the Middle East that sends crude sharply higher would do the opposite, reviving the uncomfortable combination of weaker growth prospects and tighter monetary policy.
The focus for next week will be whether this month's rate hikes represent insurance against an energy-driven inflation shock or the beginning of a lengthy global tightening cycle. If yields stabilise and oil continues lower, equities could find some breathing room. If both start climbing again, this week's recovery in risk appetite could face a much tougher test.