
AI jitters overshadow economic resilience ahead of US midterms
Technology stocks once drivethe deterioration in risk appetite ahead of the US Midterm elections.
Global markets are ending an eventful week with a growing disconnect between economic resilience and investor confidence. Central bank decisions, major technology earnings and geopolitical developments have dominated trading, but the standout theme has been the market's increasingly cautious attitude towards AI investment. Despite relatively strong US economic data, technology stocks have struggled as investors question whether the enormous sums being spent on AI infrastructure can generate sufficient returns.
The Federal Reserve left interest rates unchanged at 3.75%–4.00%, offering limited clarity on the timing of further tightening. Although the US economy grew at an annualised 3.4% in the third quarter, core PCE inflation remained elevated at 3.1%, reinforcing the difficult balance between resilient growth and persistent price pressures. Meanwhile, the ECB held its deposit rate at 2.5%, providing some relief to European equities, which have benefited from their relatively lower exposure to highly valued technology stocks. The Bank of Japan also maintained its cautious approach, leaving investors focused on the possibility of further tightening as inflation risks persist.
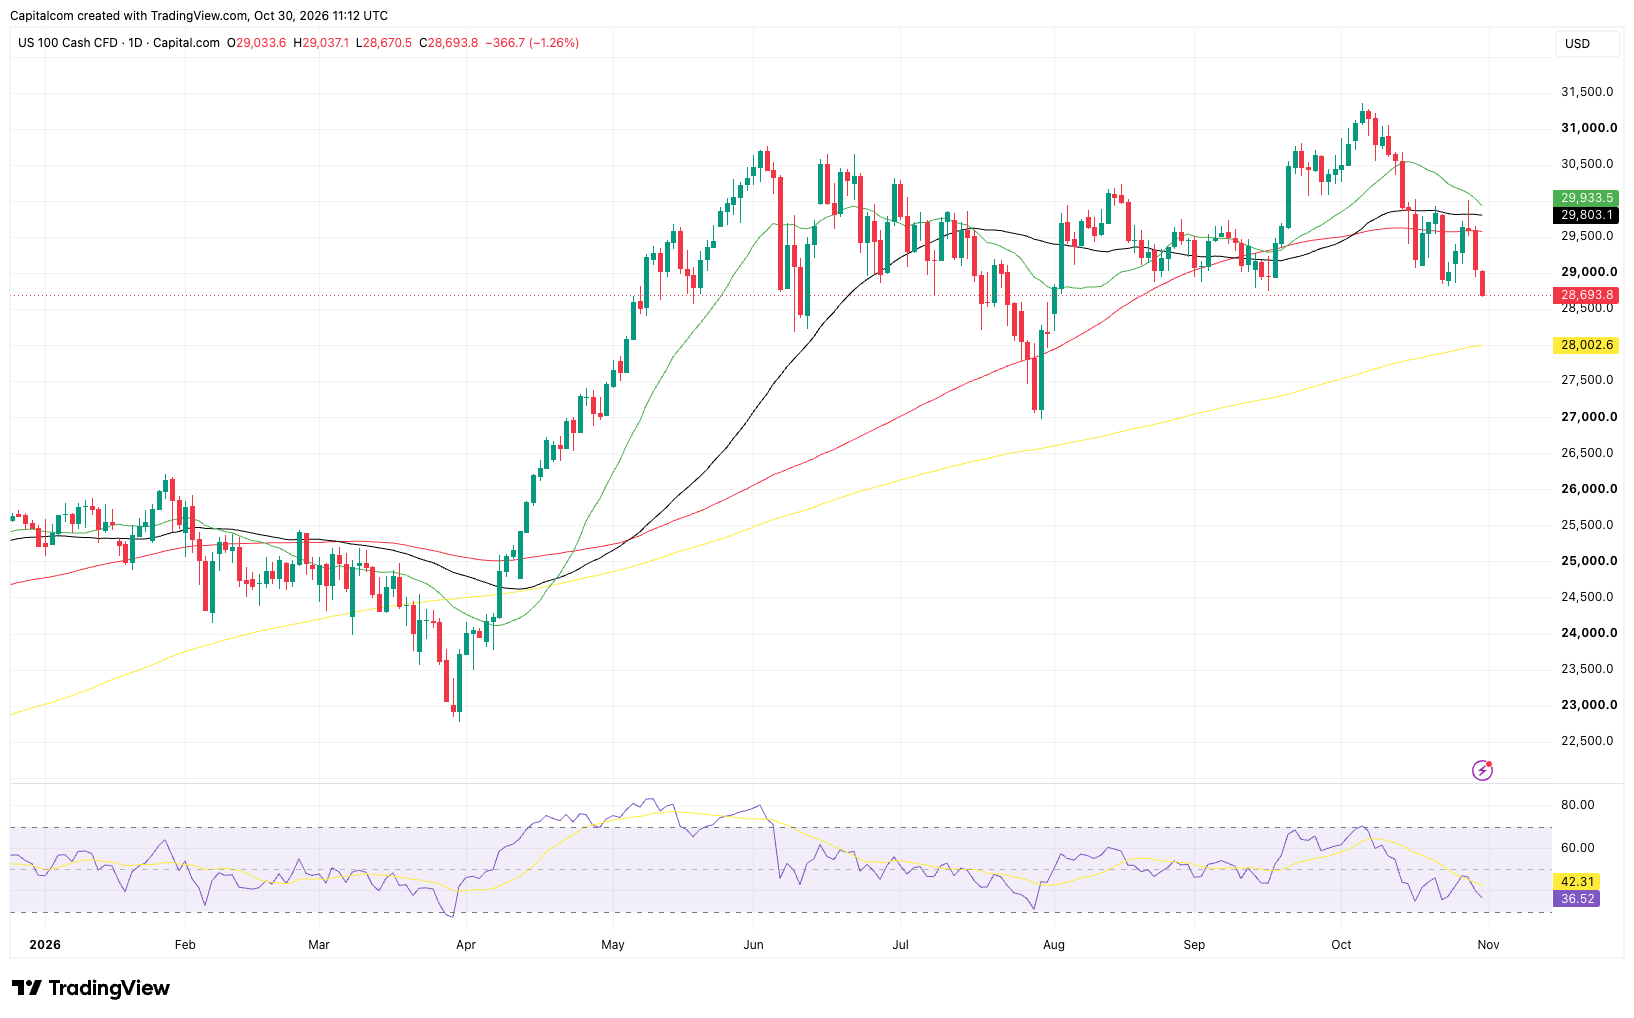
This week, Big Tech earnings have been a clear source of market uncertainty. Microsoft's results offered a more encouraging picture of AI monetisation, particularly through cloud demand, while Alphabet's sharp selloff reflected concerns about capital expenditure, profitability and cash generation. Amazon's disappointing after-hours reaction added to the pressure, reinforcing the idea that strong revenue growth is no longer enough to justify elevated valuations. Investors increasingly want evidence that AI spending is translating into sustainable earnings and free cash flow. This could remain an important challenge for the Nasdaq, particularly if Treasury yields stay elevated.
Elsewhere, the UK Budget avoided a major immediate disruption in sterling and gilts, although concerns about fiscal headroom, borrowing costs and weak growth remain. Oil markets have also been volatile as Middle East supply disruptions compete with hopes of diplomatic progress. The broader implication is that markets remain vulnerable to both inflationary shocks and shifts in risk appetite, particularly when higher energy costs threaten to keep central banks restrictive for longer.
Nasdaq 100 daily chart
Past performance is not a reliable indicator of future results.
Looking ahead: US midterms, Bank of England and employment data take centre stage
Next week could be just as consequential, although the focus will shift from corporate earnings and central bank decisions towards politics, employment data and the outlook for monetary policy.
US midterm elections: A potential turning point for fiscal expectations
Tuesday's US midterm elections will be the main political event of the week. Investors will be watching whether Republicans retain control of Congress or whether Democrats gain control of one or both chambers. The outcome could significantly influence the administration's ability to pursue further tax cuts, spending initiatives and regulatory changes.
For financial markets, the implications could be particularly important for the dollar and Treasury yields. A Congress more supportive of fiscal expansion could reinforce concerns about borrowing requirements and inflation, potentially pushing longer-dated yields higher. Conversely, divided government could limit additional spending but increase the risk of political gridlock. The biggest market reaction may come from an outcome that differs substantially from expectations, rather than the result itself.
Bank of England: Will November bring another rate hike?
The Bank of England's decision on Thursday will be another important catalyst, particularly for sterling and UK government bonds. Following September's stronger-than-expected inflation figures, markets are pricing a high probability of a 25-basis-point increase, which would take Bank Rate from 3.75% to 4.00%.
However, the challenge for policymakers is that inflation remains elevated while domestic growth is showing signs of weakness. The latest Budget has provided some clarity around fiscal policy, but the impact on borrowing costs, household spending and inflation will remain important considerations. As a rate hike is mostly priced in, the focus will be on whether the Bank signals further tightening or adopts a more cautious stance given the risks to economic activity. A hawkish message could support sterling, while concerns about growth could limit any gains.
US employment data: The next test for the Fed
Friday's US nonfarm payrolls report will provide another important indication of whether the Federal Reserve can afford to maintain its current approach. After this week's relatively inconclusive policy meeting, investors will be particularly sensitive to any evidence that the labour market is weakening or that wage pressures remain persistent.
Stronger-than-expected employment and wage growth could reinforce expectations of a December rate hike, potentially supporting the dollar and pushing Treasury yields higher. Conversely, weaker hiring could ease some pressure on interest rate expectations, although a significant deterioration in employment could also raise concerns about the sustainability of US economic growth. With markets currently pricing roughly an 80% probability of a December hike, the employment figures could prove particularly influential for both currencies and equities.
AI earnings: More scrutiny of spending and returns
Technology earnings will remain in focus, with Apple, AMD, Palantir and Qualcomm among the companies scheduled to report. Following this week's mixed reaction to major technology results, investors will be watching whether demand for AI-related products and services remains strong enough to justify continued investment. AMD's results will be particularly relevant for assessing demand for AI chips, while Apple's earnings could provide insight into consumer demand and the commercial potential of AI-enabled devices. The risk for the broader technology sector is that another round of disappointing guidance could reinforce concerns about elevated valuations.