
Michael Kramer: How to Analyse ASML Before Earnings
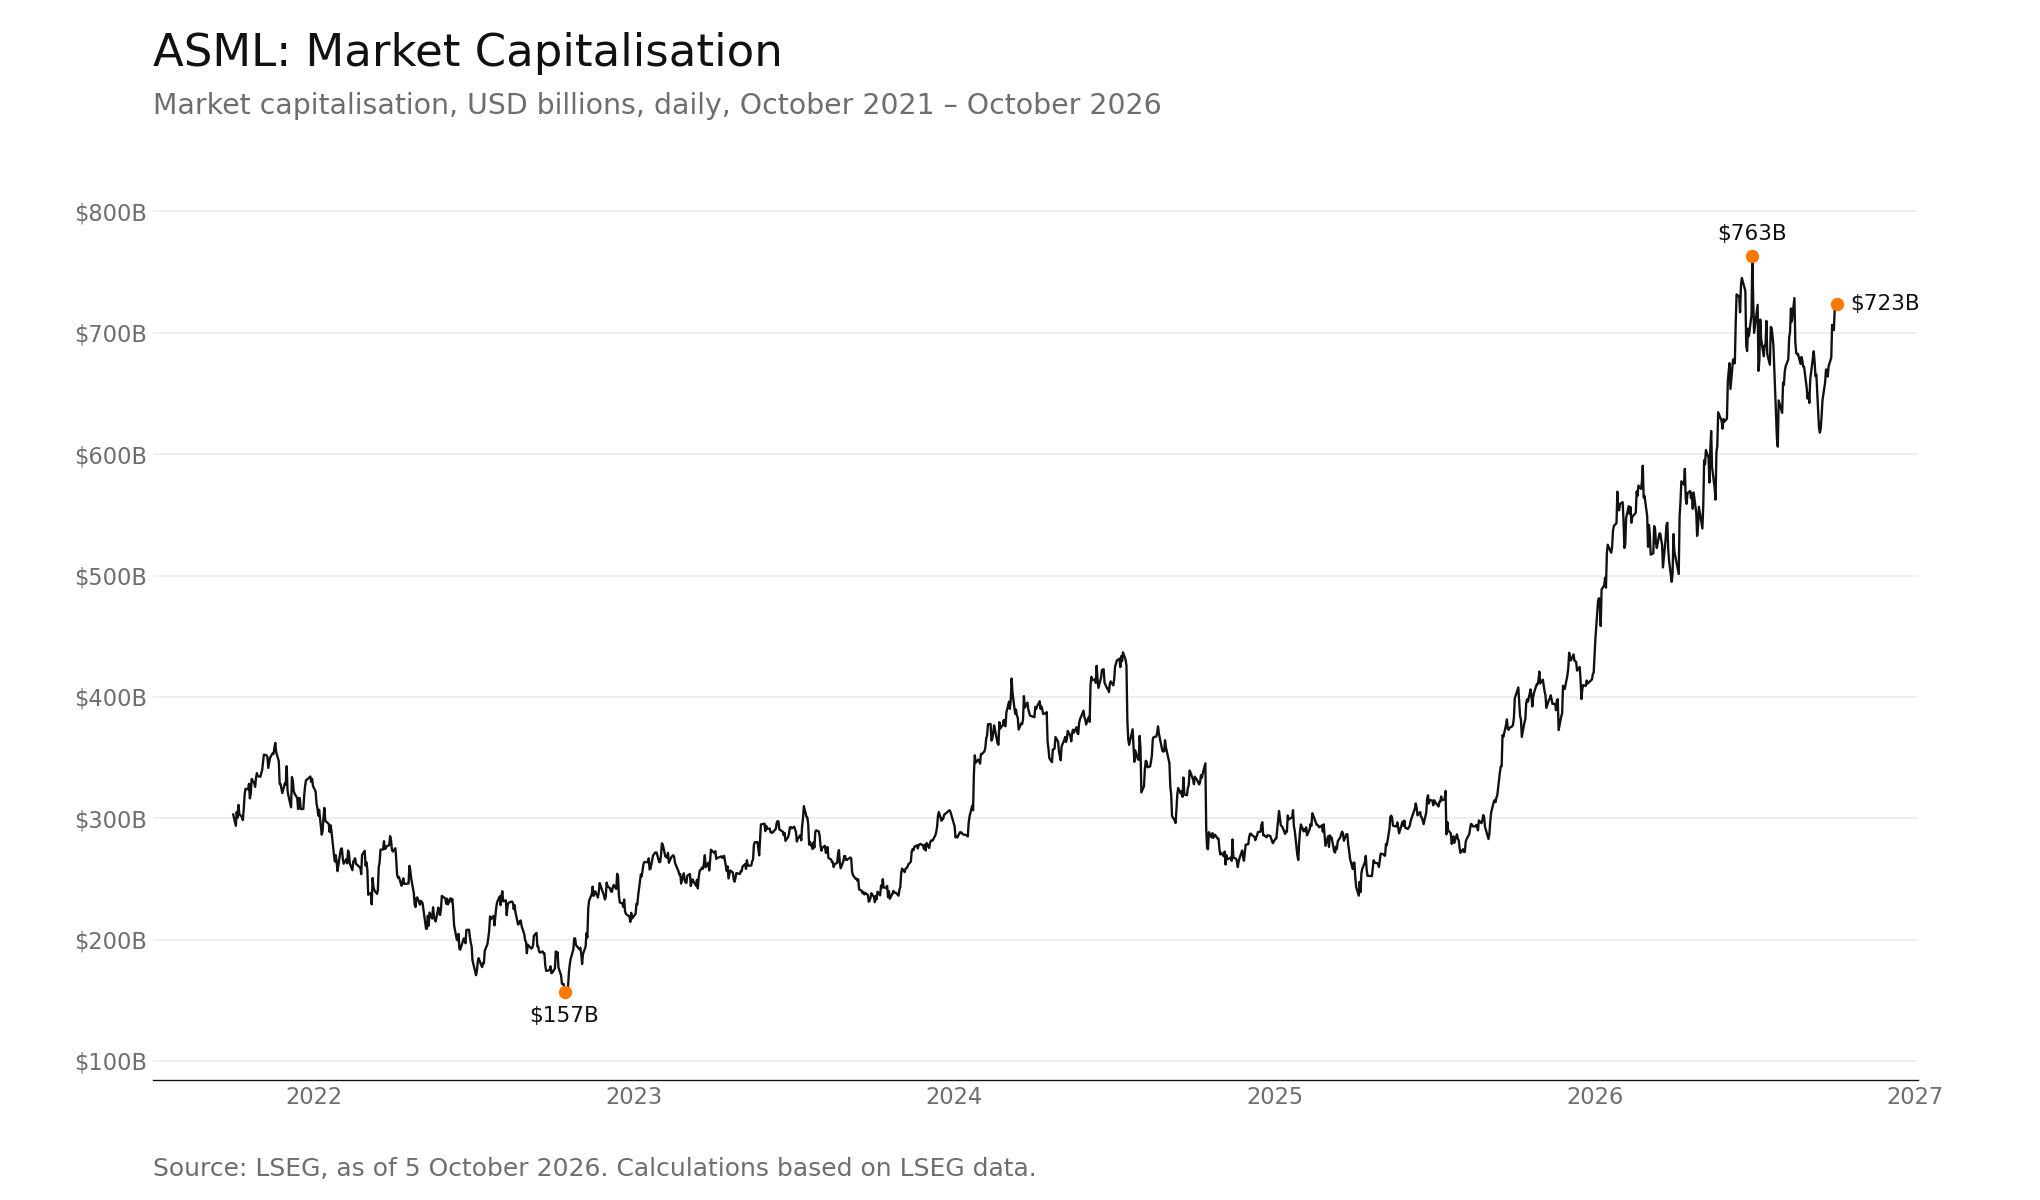
ASML’s market capitalisation has risen from roughly $157 billion in October 2022 to a 2026 peak of roughly $763 billion in June and now sits at about $723 billion as of 5 October, an increase of more than fourfold.
Revenue comes from two sources: net system sales, which include EUV and DUV lithography systems, and installed base management, which covers service and upgrades of systems already in the field.
(Source: LSEG, as of 5 October 2026. Calculations based on LSEG data)
(Past performance is not a reliable indicator of future results)
Earnings History
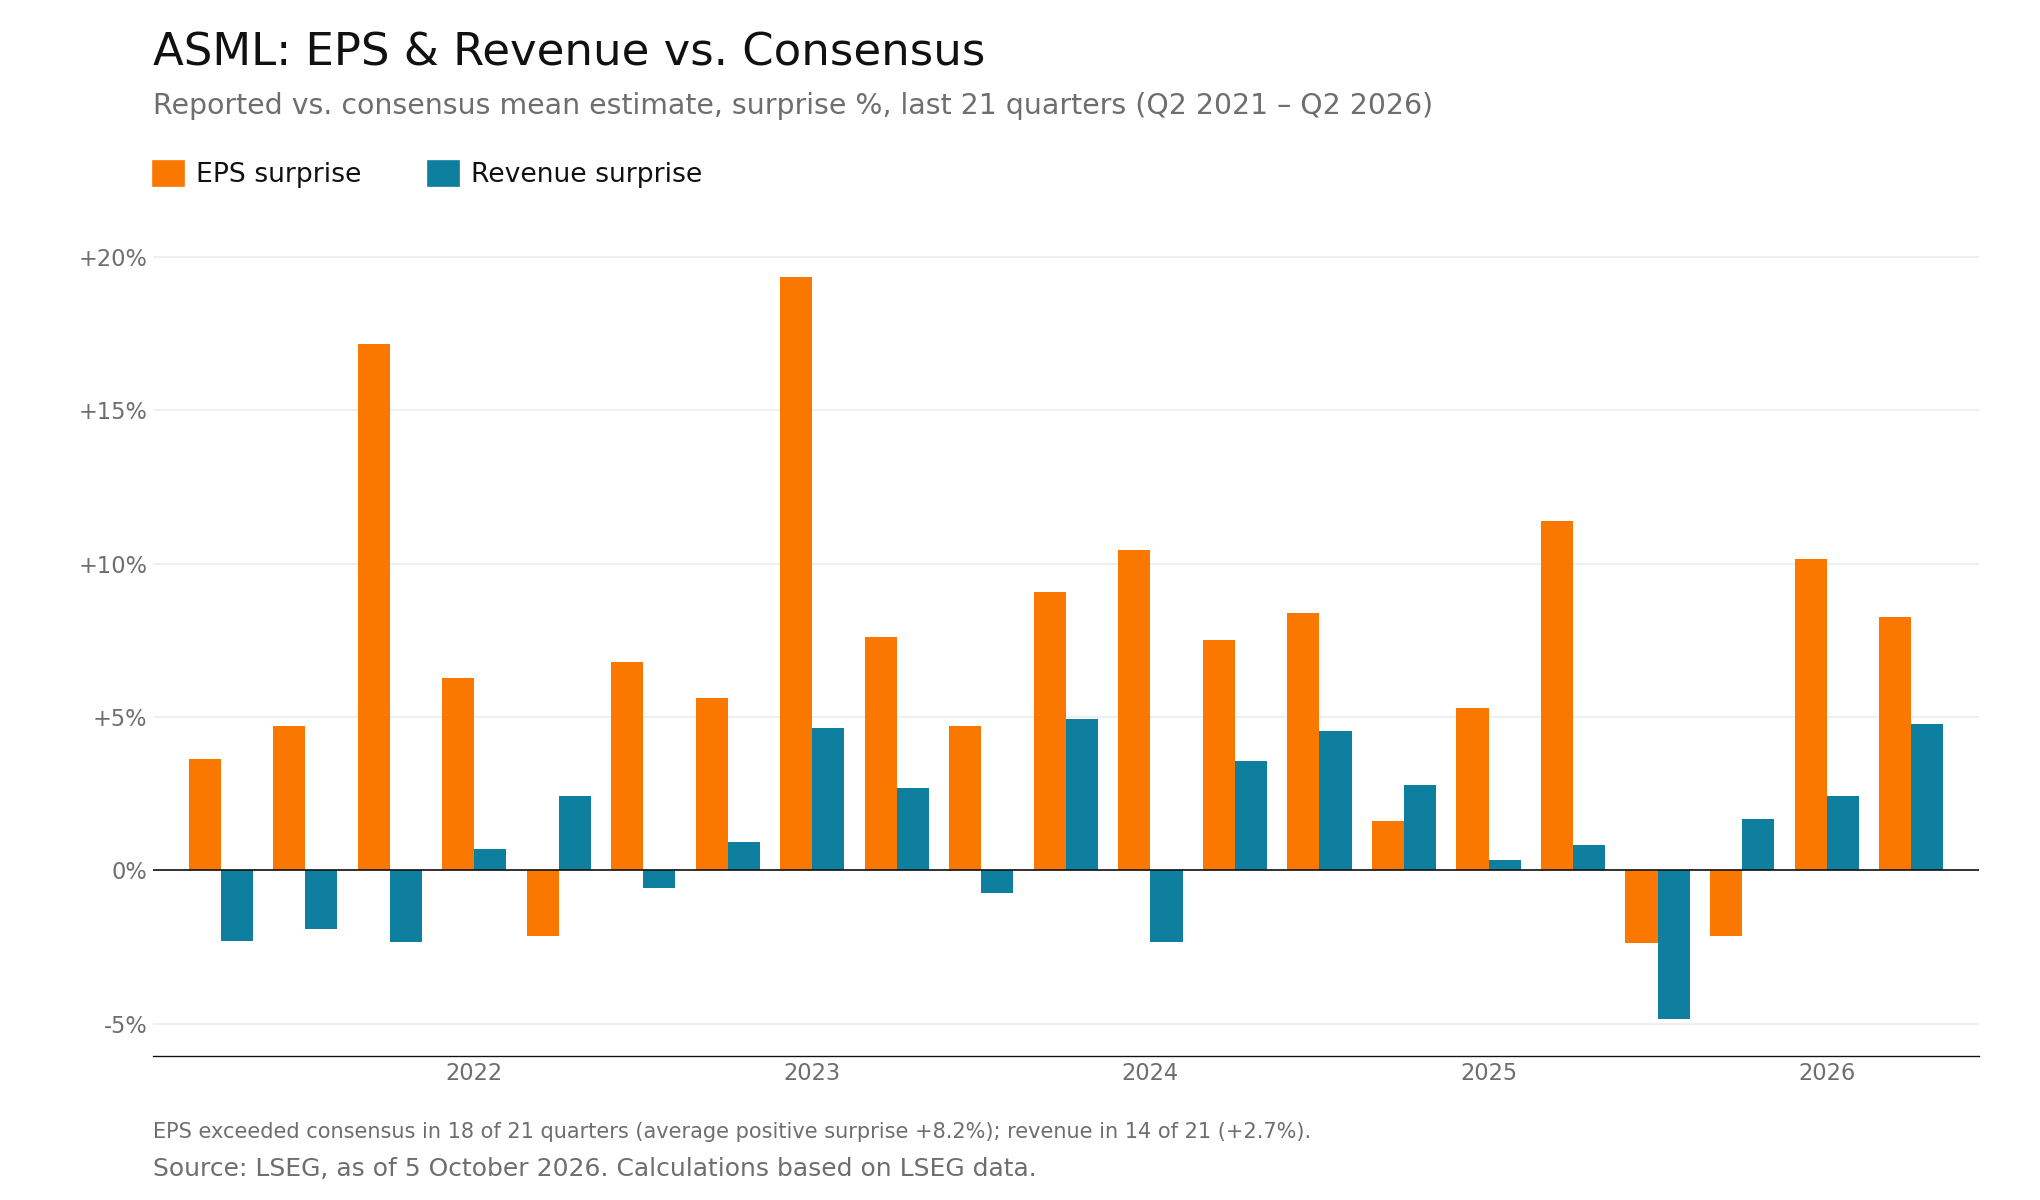
Across the 21 quarters shown, ASML’s revenue exceeded analysts’ consensus mean estimate in 14 quarters, while EPS exceeded the consensus mean estimate in 18. Among the positive surprises, EPS averaged 8.2% above consensus, while revenue averaged 2.7% above consensus.
(Source: LSEG, as of 5 October 2026. Calculations based on LSEG data)
(Past performance is not a reliable indicator of future results)
Segment Growth
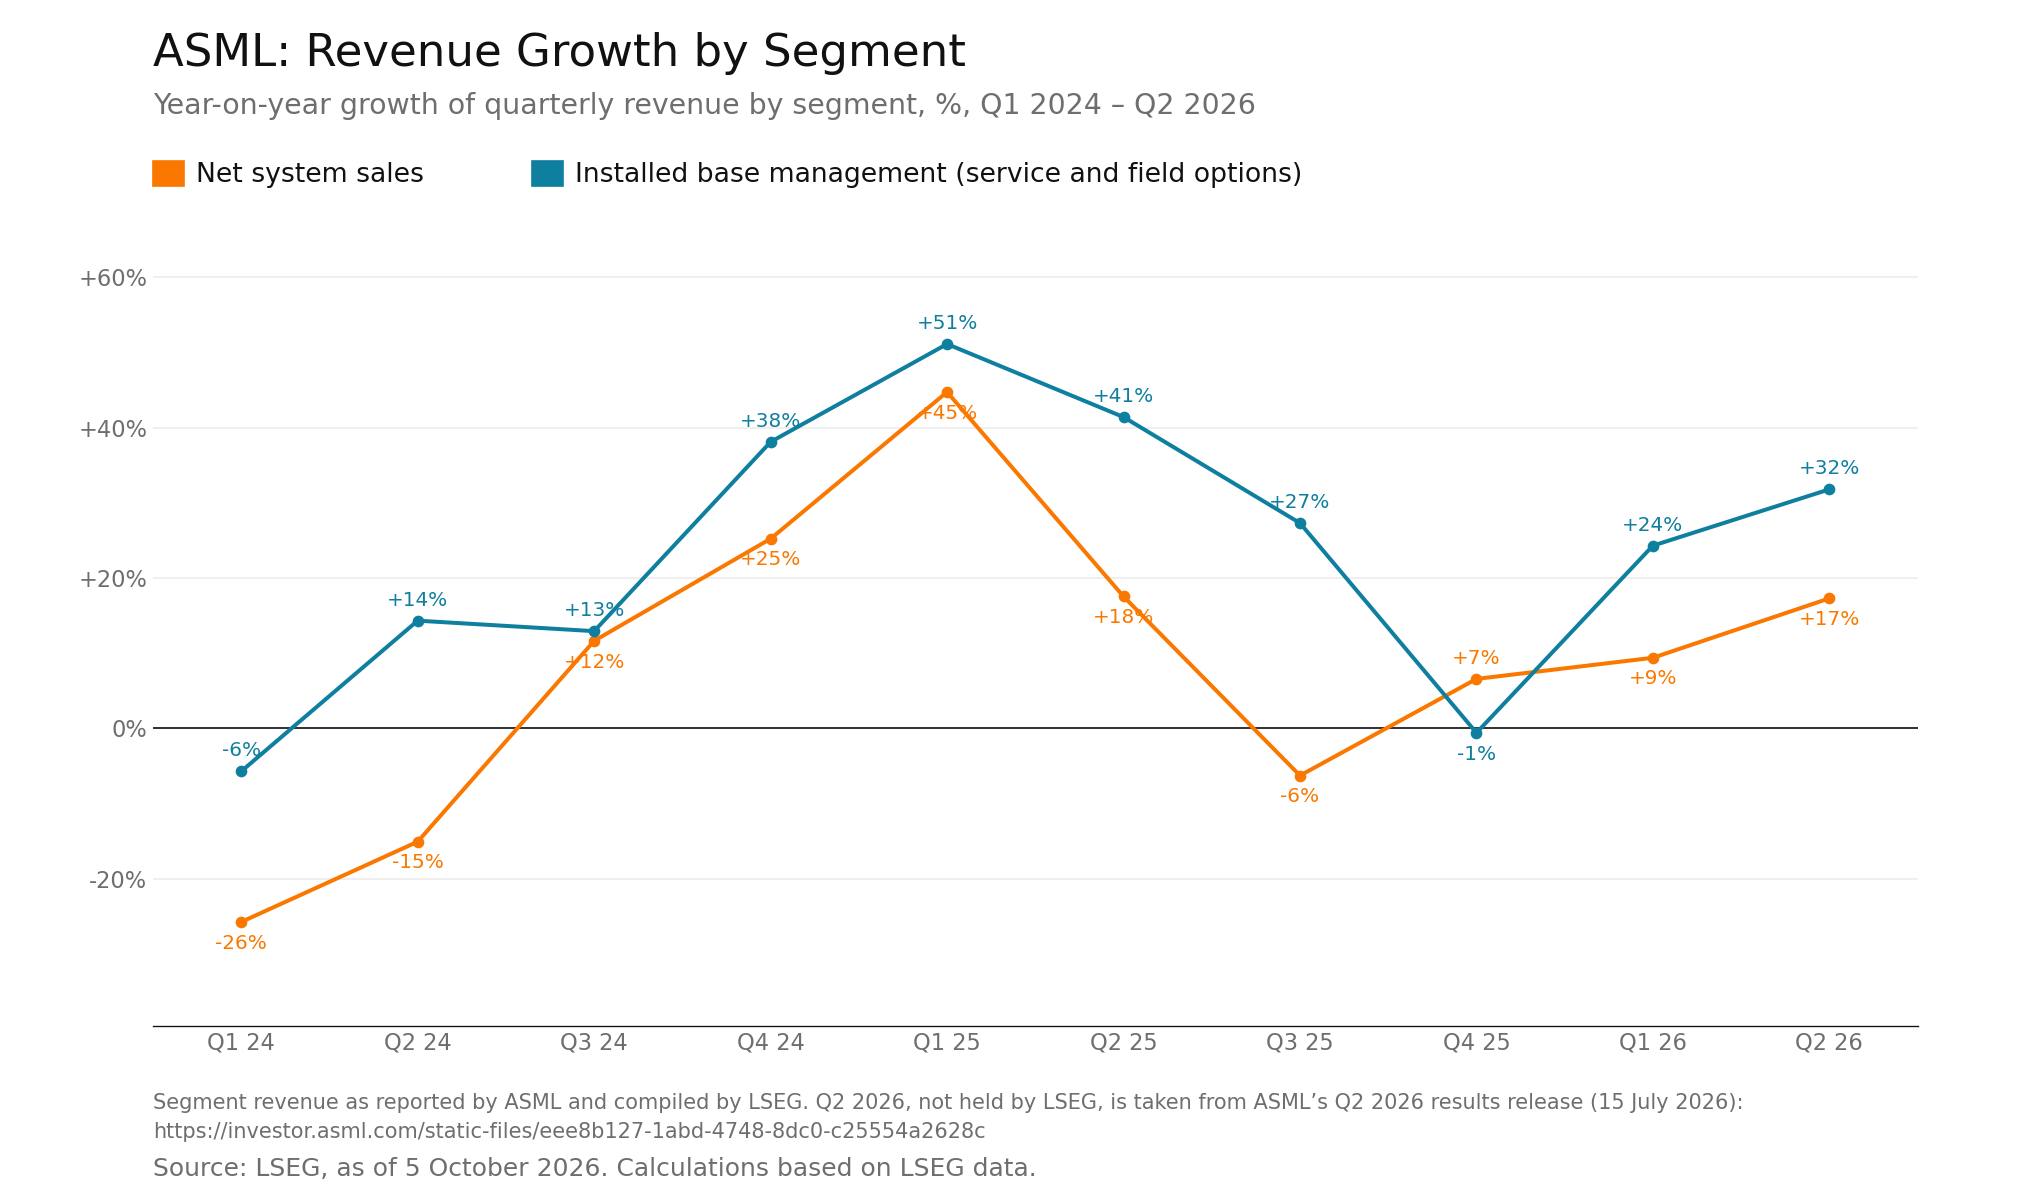
In the second quarter of 2026, net system sales grew 17.3% year on year to €6.6 billion, while installed base management revenue, which covers service and field options, grew 31.8% to €2.8 billion. Over the ten quarters shown, net system sales growth was weakest in the first quarter of 2024, when sales fell 25.8% year on year, and strongest in the first quarter of 2025, at 44.7%. Installed base management revenue fell 5.7% in the first quarter of 2024 and grew 51.1% in the first quarter of 2025, its weakest and strongest quarters over the same period.
(Source: LSEG, as of 5 October 2026. Calculations based on LSEG data)
(Past performance is not a reliable indicator of future results)
Gross Margin
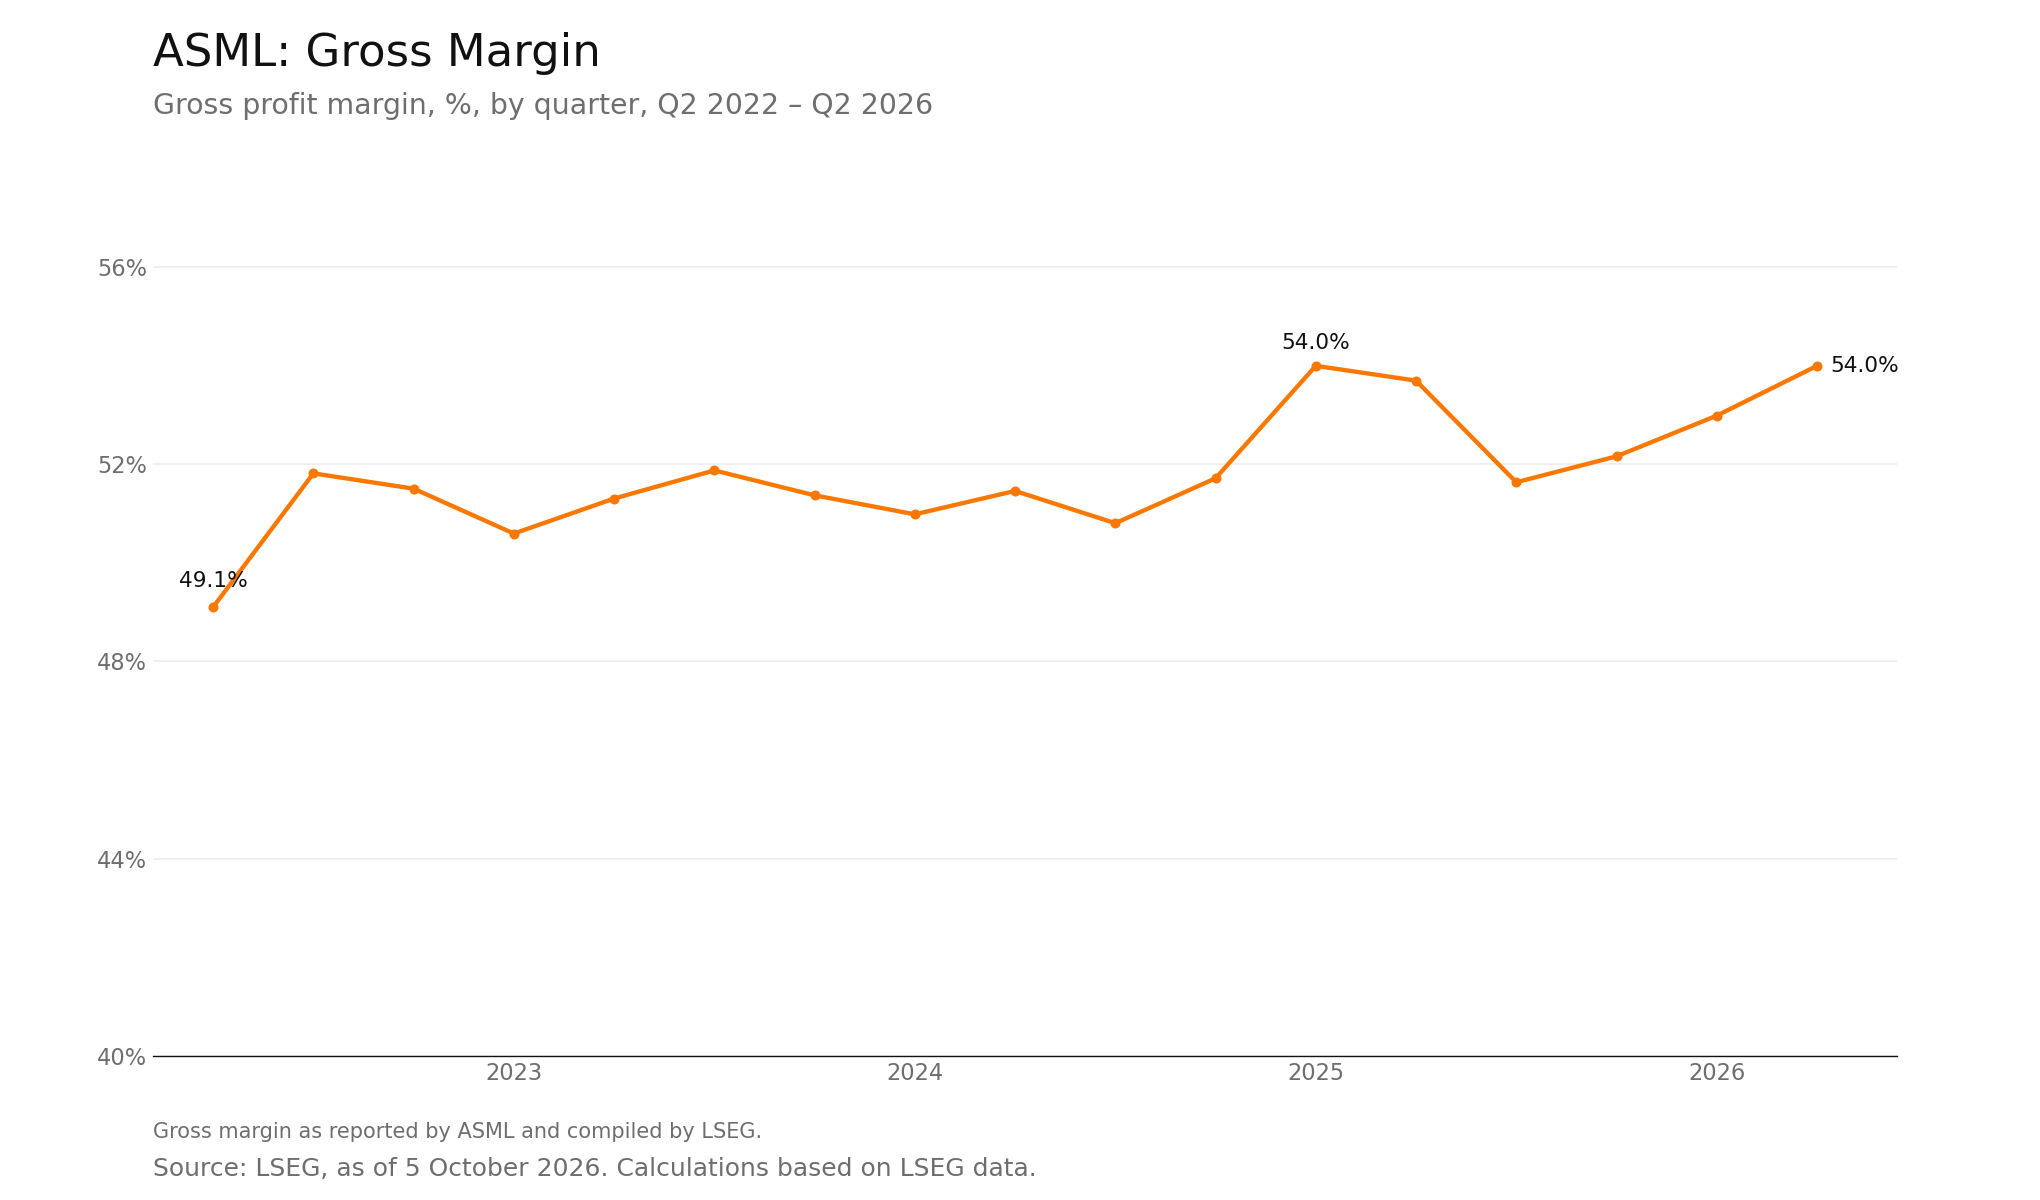
ASML’s gross margin was 54.0% in the second quarter of 2026, up from 53.7% a year earlier and matching the 54.0% of the first quarter of 2025. Over the period shown, it ranged from 49.1% in the second quarter of 2022 to 54.0%, reached in the first quarter of 2025 and again in the second quarter of 2026.
(Source: LSEG, as of 5 October 2026. Calculations based on LSEG data)
(Past performance is not a reliable indicator of future results)
Cash Flow from Operations
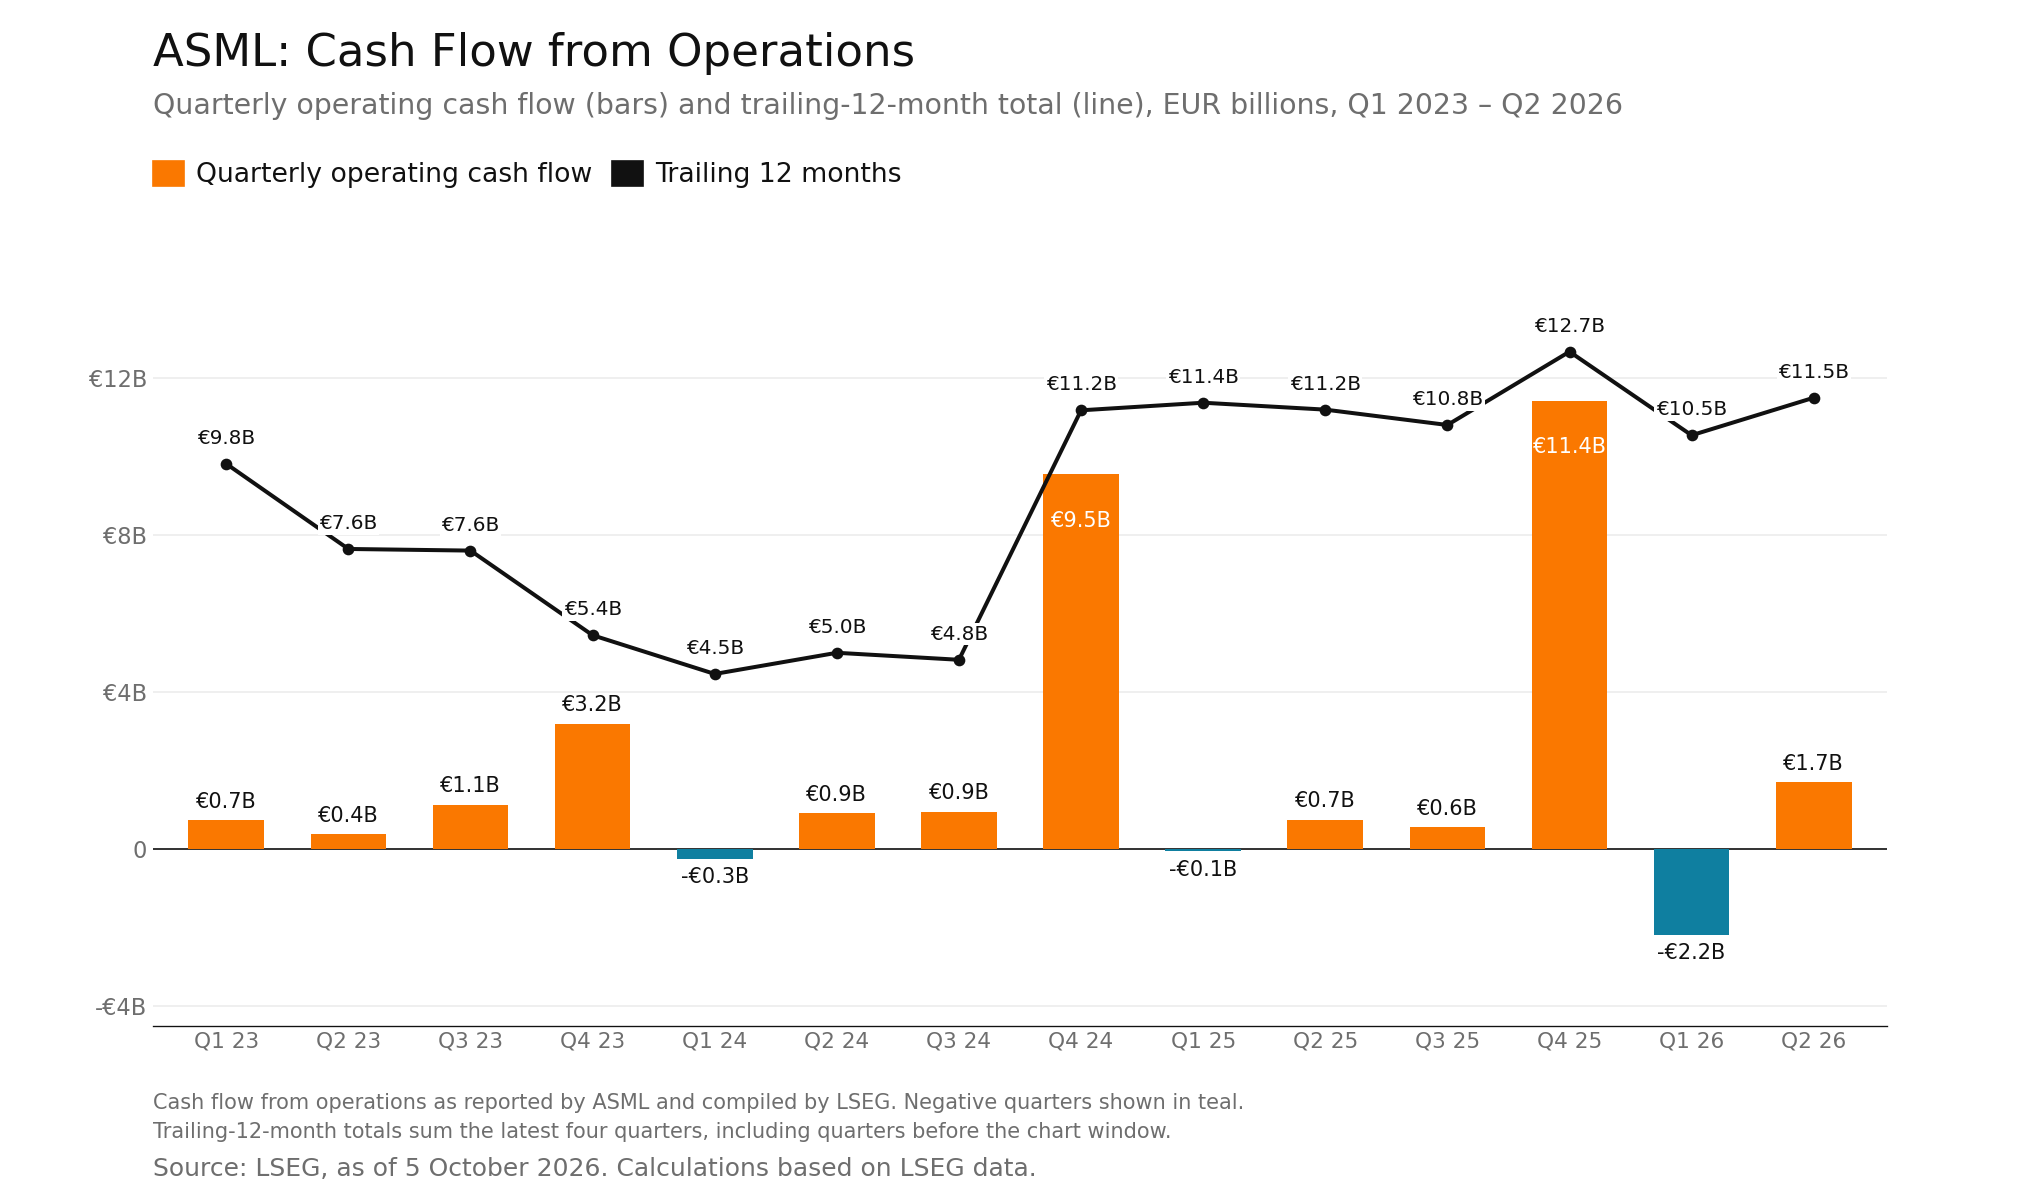
ASML’s cash flow from operations was €1.7 billion in the second quarter of 2026, compared with €0.7 billion a year earlier, after an outflow of €2.2 billion in the first quarter. On a trailing-12-month basis, operating cash flow was €11.5 billion in the second quarter of 2026, compared with €11.2 billion a year earlier and €4.5 billion at its low point in the first quarter of 2024.
(Source: LSEG, as of 5 October 2026. Calculations based on LSEG data)
(Past performance is not a reliable indicator of future results)
Options-Implied Earnings Range
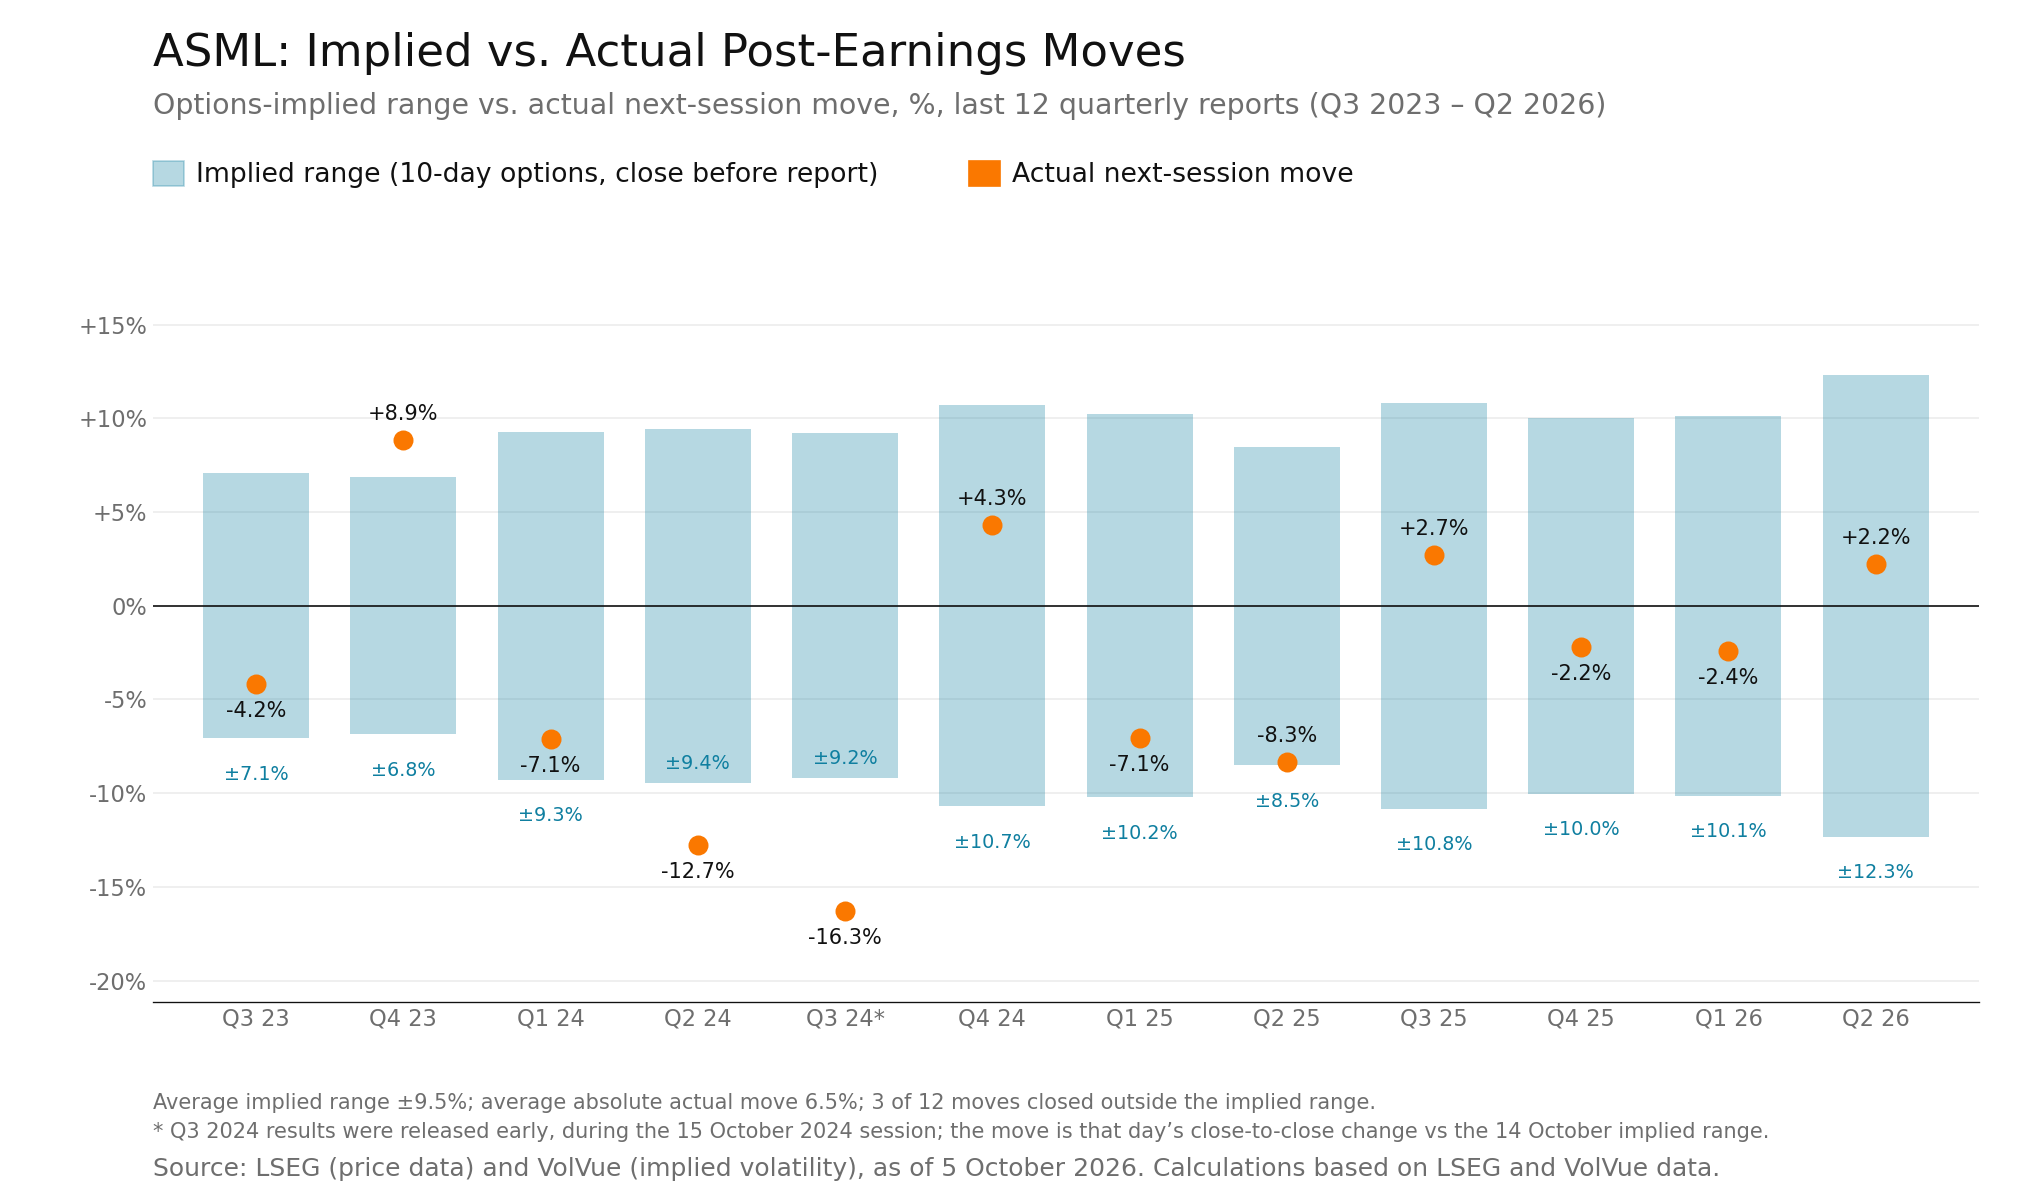
Option prices can be used to calculate an implied trading range around an earnings announcement. Across the 12 announcements shown, 10-day at-the-money implied volatility produced an average one-standard-deviation range of ±9.5%, while the average absolute realised next-session move was 6.5%. The next-session share-price move remained within the calculated range in nine cases and was outside it in three.
The implied range was estimated using the 10-day at-the-money implied volatility observed at the last close before each report, scaled to the option’s 10-day term using implied volatility × √(10/365) and applied to the share price. This produces a one-standard-deviation range derived from option prices. It does not represent a forecast or indicate the direction of the share-price move.
(Source: LSEG (price data) and VolVue (implied volatility), as of 5 October 2026. Calculations based on LSEG and VolVue data)
(Past performance is not a reliable indicator of future results)
Valuation Metrics
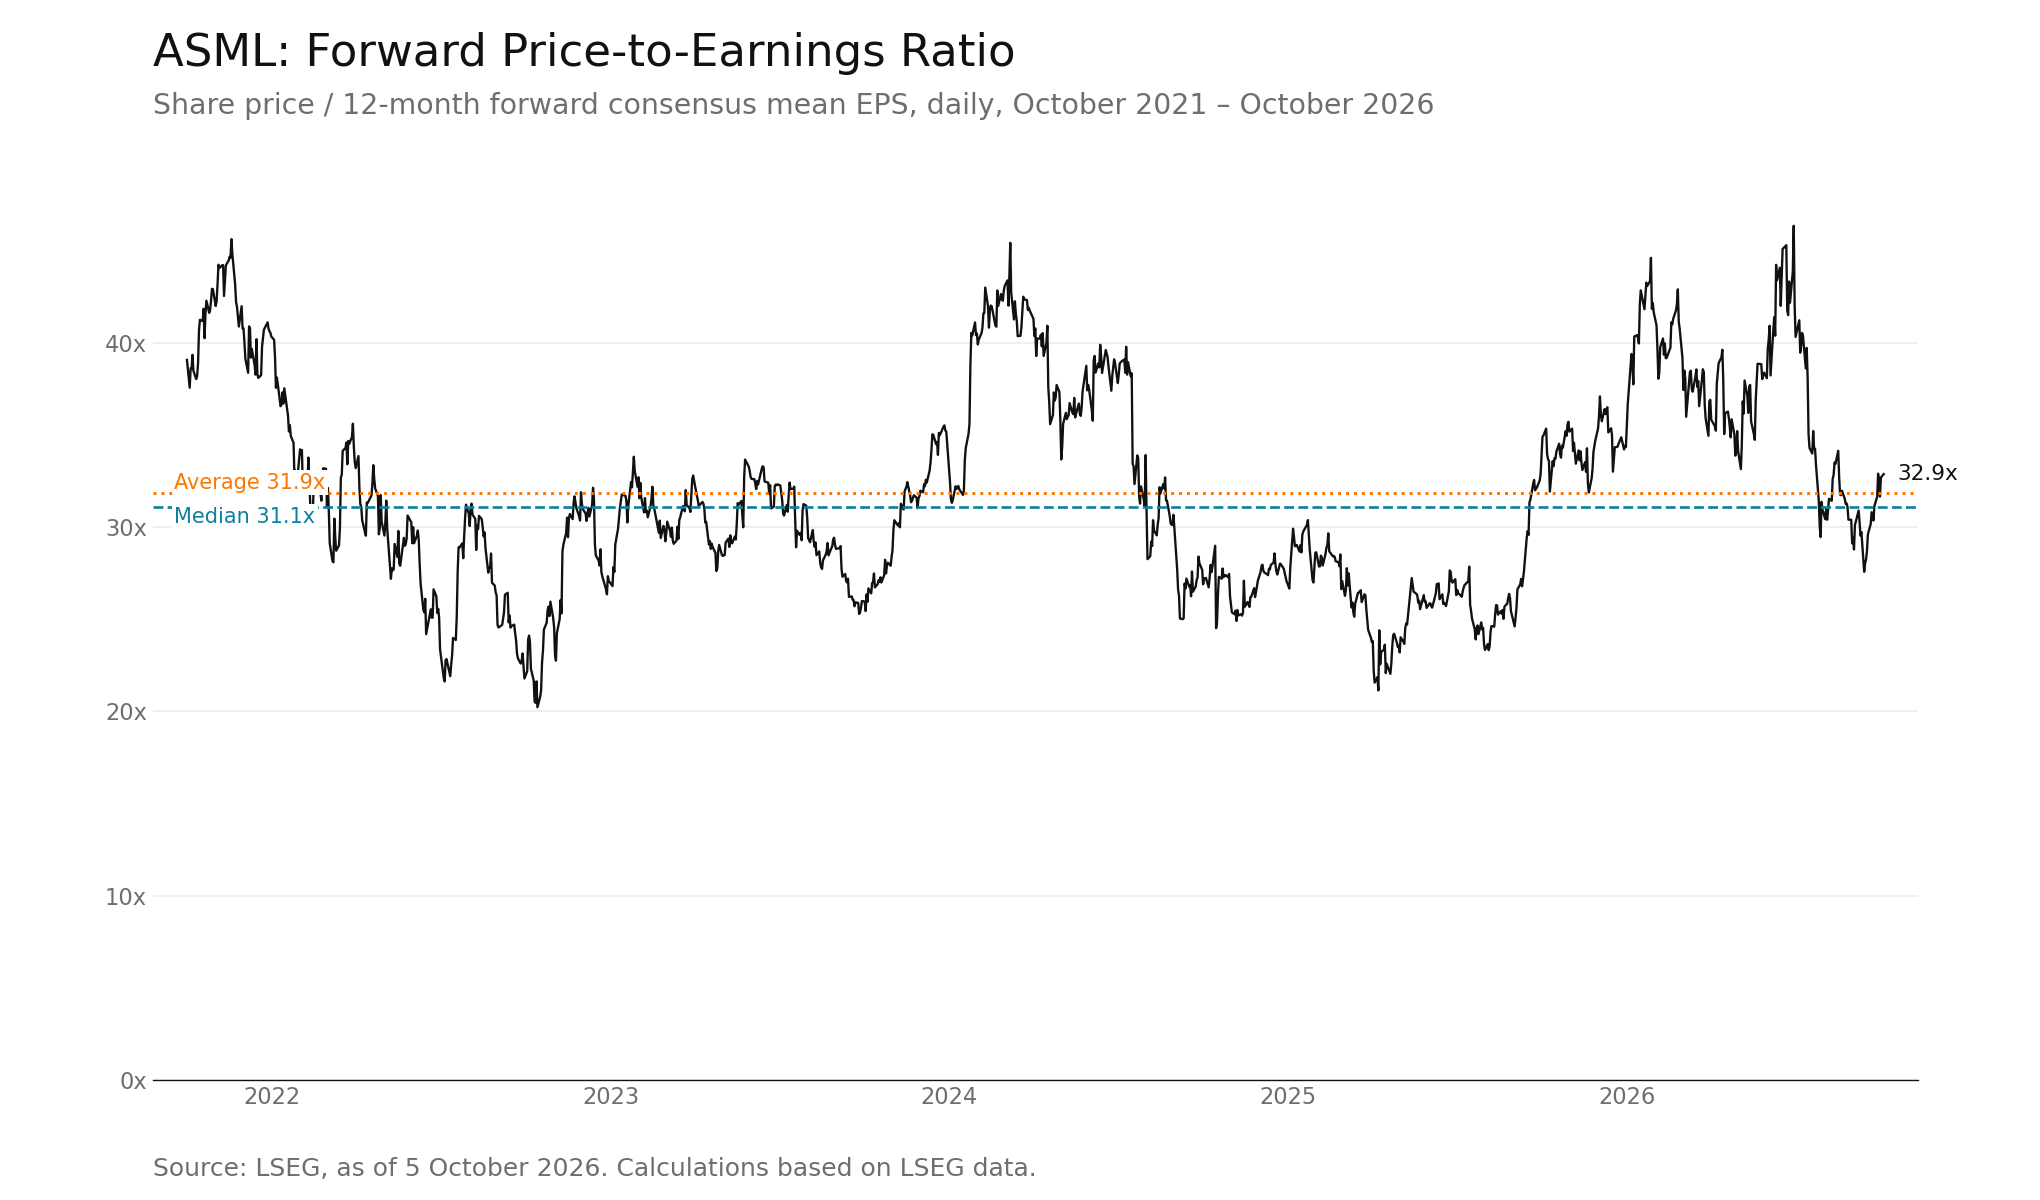
As of 5 October 2026, ASML’s forward price-to-earnings ratio, based on analysts’ estimates for the next 12 months, was 32.9. From October 2021 to October 2026, the average P/E was 31.9, and the median was 31.1, placing the 5 October observation above both measures for the period.
Historical valuation multiples provide context for how the market has priced the company over time. These comparisons do not indicate whether the shares are currently overvalued or undervalued.
(Source: LSEG, as of 5 October 2026. Calculations based on LSEG data)
(Past performance is not a reliable indicator of future results)
As of 5 October 2026, ASML’s forward price-to-sales ratio, based on analysts’ consensus mean revenue estimates for the next 12 months, was 12.0. From October 2021 to October 2026, the average P/S ratio was 9.7, and the median was 9.4, placing the 5 October observation above both measures for the period.
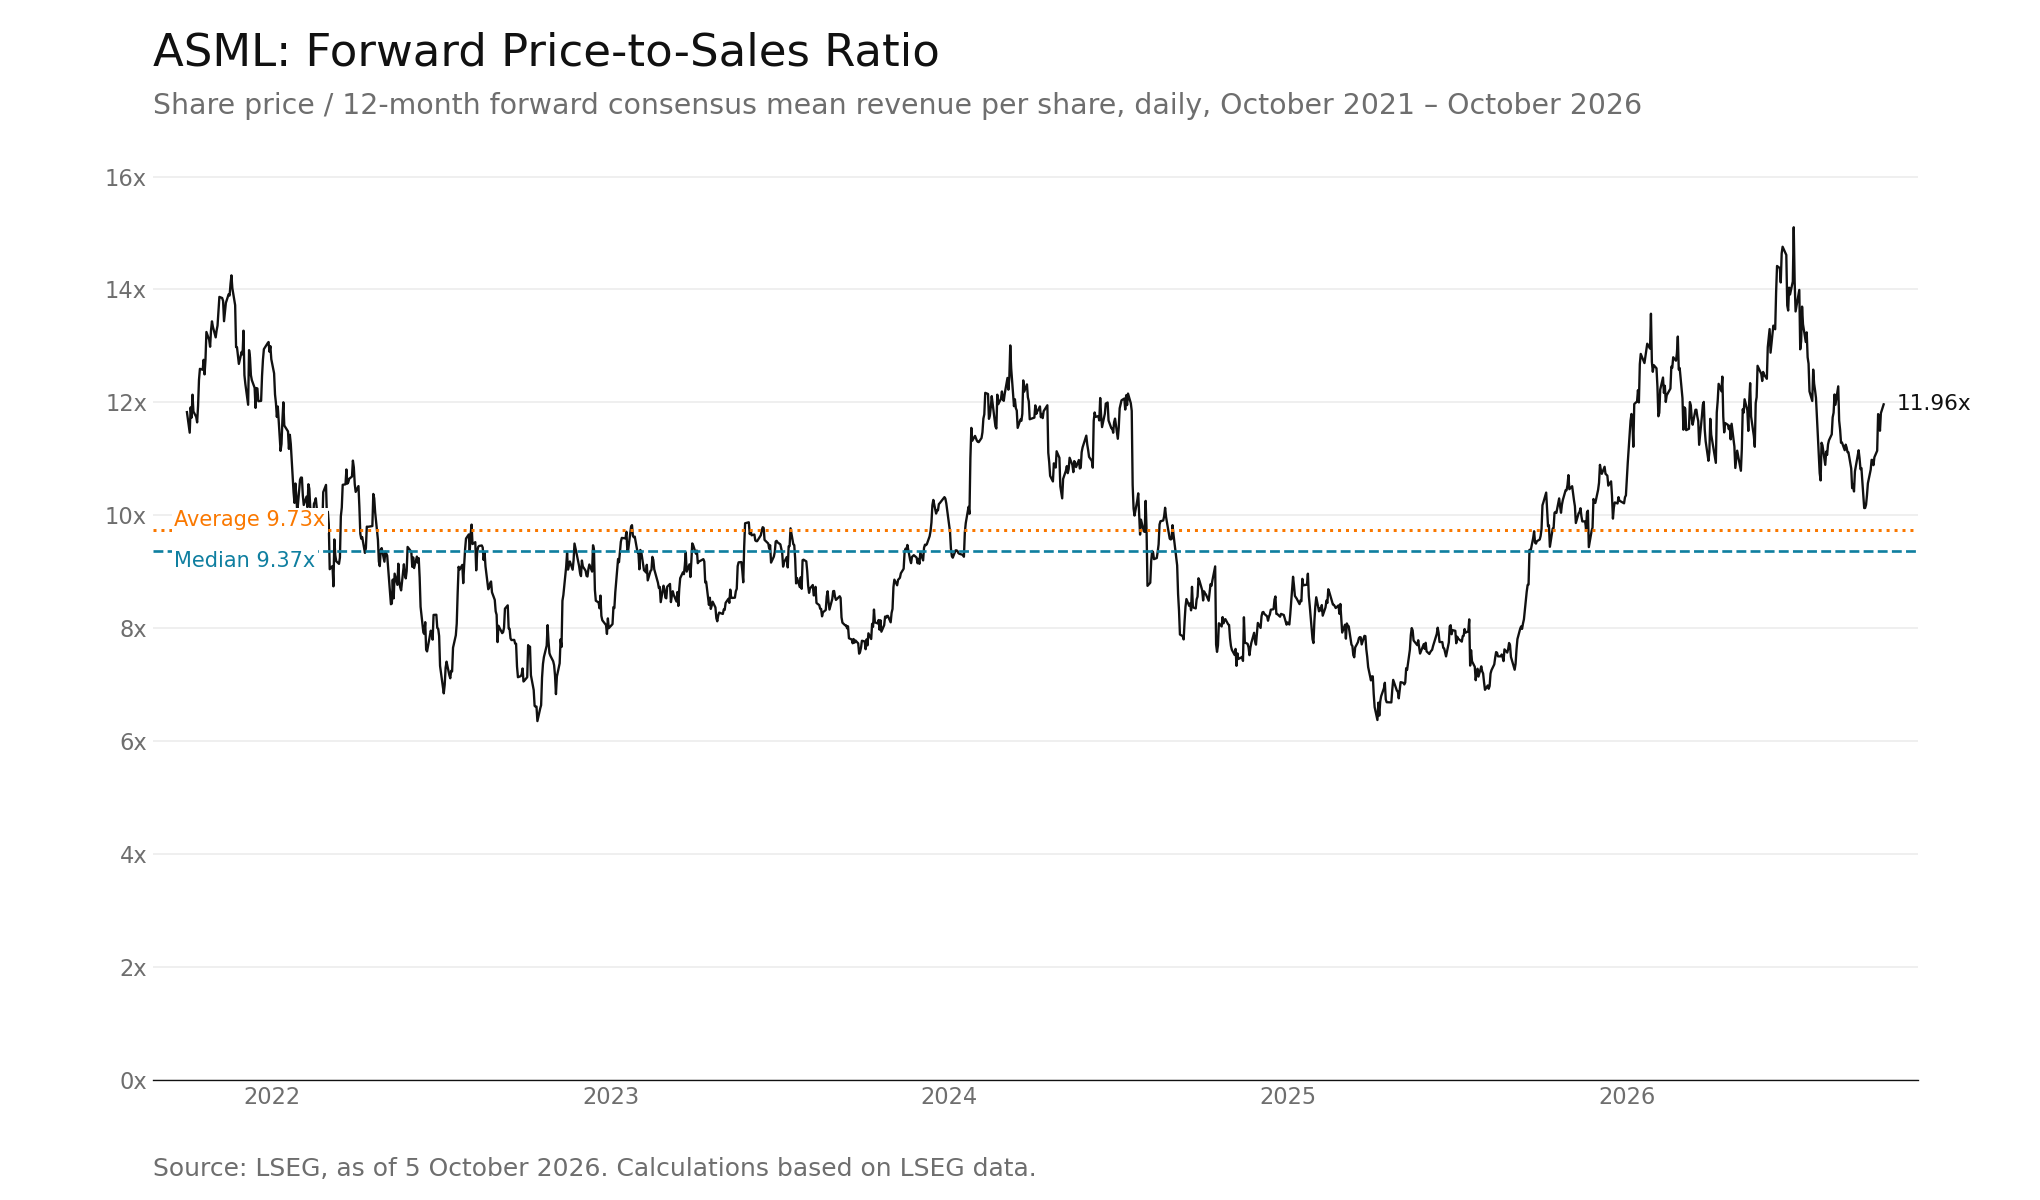
(Source: LSEG, as of 5 October 2026. Calculations based on LSEG data)
(Past performance is not a reliable indicator of future results)
Conclusion
ASML’s earnings history, revenue growth by segment, revenue mix, gross margins, operating cash flow, options-implied ranges, valuation multiples and revenue growth provide historical context ahead of the company’s third-quarter results.
As of 5 October 2026, ASML’s forward P/E and forward P/S ratios were above their respective historical averages and medians for the periods shown. These measures reflect historical observations and do not forecast the next earnings announcement. Past performance is not a reliable indicator of future results.